How to Send Money to Nigeria From Abroad (2026 Guide)

On May 1, 2026, a new Central Bank of Nigeria directive took effect: every international money transfer operator must settle diaspora remittances through naira accounts held with authorized Nigerian banks. Nigerians received $21.8 billion from abroad in 2025, and the CBN wants a bigger share of that flowing through official channels it can track and price fairly, with a stated goal of $1 billion in monthly remittances by the end of 2026.

If you send money to Nigeria regularly, or you’re doing it for the first time, that policy shift changes what “the best way to send money” actually means right now. This guide covers what changed, where transfers quietly lose value, and how the popular options compare.

This is why so many people keep searching:

  • how to send money to Nigeria from abroad
  • best app to send money to Nigeria
  • send money to Nigeria from the US or UK
  • cheapest way to send money to a Nigerian bank account

What changed for Nigeria in 2026

Before this year, some transfer operators could pay recipients out in foreign currency or route funds outside formal naira settlement. The CBN’s March 2026 directive closed that gap: as of May 1, every licensed money transfer operator must process inflows, beneficiary payouts, and related settlements through naira accounts at authorized dealer banks. The stated aim is more transparency, better price discovery in the foreign exchange market, and fewer remittances slipping through informal, unregulated routes.

For everyday senders, the practical effect is simple: recipients get paid in naira, at a rate the transfer operator sets, through an accountable banking channel. That makes the exchange rate you’re quoted, and the margin baked into it, the single biggest factor in how much your recipient actually walks away with.

Where a transfer to Nigeria quietly loses value

According to World Bank Remittance Prices Worldwide data, the average cost of sending money from the UK to Nigeria sits around 1.96 percent once fees and exchange rate margins are combined. That number sounds small until you notice it rarely tells the whole story. Four things usually eat into the total:

  • A marked-up exchange rate that’s presented as “the rate,” with no separate fee line
  • A flat sending fee on top of that already-marked-up rate
  • Delays of one to three business days, during which the naira can move against you
  • Extra charges for cash pickup versus direct bank or mobile money deposit

We cover the same pattern in more depth in our guide to choosing the best way to send money internationally: whoever quotes the number closest to the real market rate, not the flashiest app, is the one protecting your money.

How the popular options compare

Most people sending money to Nigeria end up choosing between a bank wire, Western Union, LemFi, Chipper Cash, or a Novacrust account. They all get naira into a Nigerian bank account or mobile money wallet eventually. What differs is the rate, the fee, and how long it takes.

OptionTypical speedWhere it loses money
Bank wire1 to 3 business daysHigh flat fee plus a weaker exchange rate
Western UnionMinutes to hours (cash pickup)Cash pickup fees stack on top of the rate
LemFiMinutesCompetitive, but rate varies by corridor and volume
Chipper CashMinutesBest for smaller, peer-to-peer amounts
NovacrustMinutesCompetitive rate with no cash pickup markup

Example: sending $500 to a Nigerian bank account

Say the market exchange rate values $500 at a certain naira amount. A transfer with a 4 to 6 percent all-in margin, common across banks and several apps, quietly removes $20 to $30 of that before it lands. Add a flat fee of $5 to $15, and the gap between “what you sent” and “what they received” grows fast, especially if you’re sending every month.

This is also where the exchange rate itself matters beyond the transfer fee. If you’re regularly comparing naira quotes, our breakdown of which app gives the best USD to naira exchange rate walks through how to tell a fair quote from a padded one.

Why freelancers and diaspora senders use Novacrust

A Novacrust account lets you hold US dollars and send to Nigeria, or to 50+ other countries, without stacking a separate bank, card, and remittance app on top of each other. You can:

  • Receive USD directly from international clients, Upwork, Fiverr, or a US employer
  • Convert to naira at a competitive rate, in the same account
  • Send to a Nigerian bank account or mobile money wallet in minutes

If you don’t have a US dollar account set up yet, our guide to opening a USD Account online in minutes covers what you need before your first transfer, no US address required.

Other ways dollars reach Nigeria

A bank transfer isn’t the only route into naira. Two worth knowing:

  • Gift cards. If you’re paid in US gift cards, or received one as a gift, selling gift cards for naira in Nigeria turns that value into cash without a wire transfer at all.
  • Stablecoins. Some senders convert USDT or USDC to naira directly, skipping the traditional banking rail entirely. Our guide on converting crypto to naira covers how that works end to end.

FAQ: sending money to Nigeria in 2026

Do Nigerians receive remittances in dollars or naira now?

As of May 1, 2026, licensed money transfer operators must settle remittances through naira accounts at authorized Nigerian banks. In practice, that means recipients are paid out in naira rather than foreign currency cash.

What’s the cheapest way to send money to Nigeria?

The cheapest option is usually whichever one quotes an exchange rate closest to the real market rate and charges a transparent, separate fee rather than folding its margin into the rate itself. Direct bank or mobile money deposit is almost always cheaper than cash pickup.

How long does a transfer to a Nigerian bank account take?

Bank wires typically take one to three business days. Apps built for cross-border transfers, including Novacrust, usually settle in minutes once the sender’s funds are confirmed.

Is it safe to send money to Nigeria through an app instead of a bank?

Licensed transfer operators now settle through naira accounts at authorized dealer banks under CBN oversight, so a regulated app is not inherently less safe than a bank wire. Check that any provider you use is licensed for the corridor you’re sending through.

Can I still send money to Nigeria in US dollars?

You can send from a USD account or balance, but under the 2026 rules the recipient is paid out in naira through the receiving bank. Holding dollars in your own account and converting only when you’re ready to send is still a valid way to manage timing.

Final thoughts

The 2026 naira settlement rule makes one thing clearer than before: the exchange rate you’re quoted, not the brand name on the app, decides how much of your money actually reaches Nigeria. With $21.8 billion in diaspora remittances already flowing through official channels in 2025, and the CBN pushing for more, comparing the real rate before you send is worth the extra minute every time.

Sign up to get started on Novacrust here.
Which App Gives the Best USD to GHS (Cedi) Exchange Rate?

On 30 December 2025, the Bank of Ghana’s official interbank rate put the dollar at GHS 10.45. Check a live market rate today and the cedi is trading closer to GHS 11.75 to the dollar, over 12 percent weaker in about seven months. That gap is before any bank or app adds its own margin on top.

This is why so many people in Ghana and the diaspora keep searching:

  • usd to ghs rate today
  • dollar to cedi rate today
  • best app to convert usd to cedis
  • wise vs grey ghana rate

The real problem is not finding the day’s rate. It is how many cedis you actually keep after conversion, once fees and margins get added on top of the number you saw online.

This guide breaks down why your bank rate never matches the rate you googled, how the popular apps handle USD to GHS conversion, and what actually protects your money.

Why the rate you see online is not the rate you get

Ghana runs on two different reference rates, and mixing them up is where most people lose money.

  • The official interbank rate. Published daily by the Bank of Ghana, this is the benchmark rate banks trade at with each other. It is not the rate you get at a bank counter or on a card.
  • The live market mid rate. Sites like XE track this in real time. It moves faster than the interbank rate and is closer to what money changers and street rates reflect.

Every bank, card network, and remittance app then adds its own margin on top of one of these two numbers. That margin, not the headline rate, is what decides how many cedis land in your account.

Where you lose money on USD to GHS conversion

The losses usually come from the same four places:

  • A hidden margin baked into the “exchange rate” instead of a separate fee
  • Multiple conversion steps between USD, a middle currency, and cedis
  • Mobile money or bank withdrawal charges on top of the conversion
  • Delays that force you to convert at whatever rate applies days later

We broke down this exact problem for the naira side of the market, and the pattern in Ghana is identical: freelancers focus on getting paid in dollars and pay almost no attention to what happens the moment those dollars become cedis.

How popular apps handle USD to GHS conversion

Most people receiving dollars in Ghana end up choosing between a handful of options: Wise, Payoneer, Grey, or a Novacrust USD Account. Each converts USD to GHS, but the cedis you walk away with can differ by a meaningful amount because of how each one prices the conversion.

PlatformEffective rate you getCedis received
WiseSlightly below marketLower payout
PayoneerIncludes a wider marginLower payout
GreyCloser to marketBetter payout
NovacrustCompetitive rateHigher payout

Example: converting $1,000 to cedis

Assume the market rate is GHS 11.75 to the dollar. On paper, $1,000 should become GHS 11,750. In practice, a 2 to 4 percent margin, which is common across banks and several apps, quietly takes GHS 235 to 470 off that number before it ever reaches your account.

That is the entire game. It is not about who lets you receive dollars the fastest. It is about who takes the smallest cut turning those dollars into cedis.

Why freelancers and remote workers in Ghana use Novacrust

A Novacrust USD Account removes the extra hops between getting paid and holding cedis you can actually spend.

With it, you can:

  • Receive USD directly from clients, Upwork, Fiverr, or platforms that pay in dollars
  • Convert to cedis at a competitive rate inside the same account
  • Withdraw to your Ghanaian bank or mobile money wallet in minutes

If most of your income already comes from international clients, this guide to the best payment setup for Upwork and Fiverr work in Africa covers how to get paid in the first place, before conversion even comes into it.

Other ways Ghanaians turn dollars into cedis

Currency conversion is not the only way dollars reach Ghana. Two common ones worth knowing about:

  • Gift cards. If you receive US gift cards as payment, a tip, or a refund, selling gift cards for cash in Ghana converts that value to cedis without needing a US bank account at all.
  • Direct transfers. For money sent from family or clients abroad rather than earned as a freelancer, our guide to sending money internationally covers bank transfer and mobile money delivery across Ghana and the rest of the region.

FAQ: USD to GHS exchange rate

What is the actual USD to GHS rate today?

The Bank of Ghana publishes an official interbank rate daily. Live market trackers like XE update faster and tend to sit closer to what you will actually be quoted. Neither one is the rate you receive after a platform adds its margin.

Why does my bank’s rate differ from what I see online?

Banks price in a spread on top of the interbank rate to cover their own risk and margin. That spread is rarely shown as a separate line item, so it looks like the “rate” itself is different, when really a fee is baked in.

Is Grey or Wise better for converting USD to GHS?

Both are usable options and generally beat a traditional bank. Grey tends to price closer to the market rate than Wise for cedi conversions, but neither is built specifically around receiving USD and cashing out to Ghanaian mobile money in one step the way a USD Account is.

Should I convert to cedis immediately or hold dollars?

Given how much the cedi has moved against the dollar over the past year, holding part of your income in USD and converting only what you need for the month is a common way freelancers protect their earnings from further depreciation.

Do mobile money withdrawals cost extra on top of conversion?

It depends on the platform. Some charge a separate withdrawal fee on top of the conversion margin, which is another silent way your payout shrinks. Always check both numbers, not just the rate.

Final thoughts

Getting paid in dollars is only half the job. What you keep after conversion is what actually lands in your pocket, and with the cedi moving as much as it has, that difference compounds fast.

Choosing a USD Account built for this, instead of stacking two or three apps between your client and your cedis, is how you stop losing money you never noticed leaving.

Sign up to get started on Novacrust here.
The Best Apps to Buy and Sell USDT and USDC in Africa (2026)

Sell $500 of USDT through the wrong app, and you can lose $15 to $25 of it before the money even reaches your bank account. Not because the coin moved, but because of a widespread withdrawal fee, or a slow payout that forces you to accept a worse rate. Buying and selling stablecoins in Africa isn’t hard anymore. Picking the app that doesn’t quietly eat your money is the actual problem.

Here’s a straight comparison of the apps people across Nigeria, Kenya, Ghana, and beyond actually use for USDT and USDC, and what each one is genuinely good at a

Six rules for not losing money on your next crypto trade

  1. Check the spread, not just the “fee.” Many apps advertise 0% fees but bake their margin into the buy/sell rate. Compare the actual NGN, KES, or GHS amount you’d get, not the headline fee.
  2. Confirm your payout method is actually supported. Bank transfer, mobile money (M-Pesa, Airtel Money), and card funding aren’t universal across every app in every country.
  3. Check withdrawal speed before you need it. An app that takes a day to release your cash is a different product than one that pays out in minutes, even if the rate looks identical.
  4. Look for local licensing or clear regulatory standing. This matters more in Nigeria and Kenya than it used to, and it’s the difference between an app you can trust with rent money and one you use for small amounts only.
  5. Don’t ignore P2P if you’re trading larger amounts. Platforms with deep P2P liquidity (Binance, Bybit, Bitget) often beat dedicated apps on price once you’re moving a few hundred dollars or more.
  6. Test with a small trade first. Rates, speed, and support quality on paper don’t always match reality. A $20 test trade tells you more than any comparison table.

The apps, compared

Yellow Card

Pan-African coverage across more countries than most competitors, with strong local payment rails: bank transfer and mobile money in many markets. A solid default if you’re new to crypto and want one app that works whether you’re in Lagos or Nairobi.

Quidax and Busha

Both built specifically for the Nigerian market, with NGN rails and local support. Good if Nigeria is your only market and you want a straightforward buy/sell flow without needing P2P.

BitAfrika

Covers Ghana and Nigeria with a simple buy/sell/send flow across a wide range of coins, not just USDT and USDC. Worth a look if you want one app for stablecoins and other assets like BTC or ETH.

Binance P2P, Bybit, and Bitget

The deepest liquidity of any option here, with active P2P markets in Kenya, Ghana, and South Africa. Best for people comfortable navigating a P2P interface and trading larger amounts where price matters more than simplicity.

Novacrust

Buy, sell, and deposit USDT, USDC, BTC, ETH, and SOL directly on Novacrust, in the same app you’d use for a USD Account, gift cards, or sending money to 50+ countries. If you’re already moving money internationally, converting stablecoins in the same place you hold and spend it removes a step other apps can’t.

Which one should you actually use?

SituationBest fit
New to crypto, want simplicityYellow Card
Nigeria-only, straightforward buy/sellQuidax or Busha
Want stablecoins alongside other crypto and everyday finance in one appNovacrust
Trading larger amounts, comfortable with P2PBinance, Bybit, or Bitget
Ghana or Nigeria, want broad coin supportBitAfrika

FAQ

What’s the cheapest way to sell USDT in Africa?

It depends on the amount. For small trades, a dedicated app like Yellow Card or Novacrust with a tight spread usually beats P2P once you account for time and hassle. For larger amounts, deep P2P liquidity on Binance, Bybit, or Bitget often wins on price.

Is it safe to buy and sell USDT or USDC through these apps?

Stick to apps with clear regulatory standing in your country, visible company information, and a track record of fast payouts. Test any new app with a small trade before moving larger amounts through it.

Can I buy USDT or USDC with mobile money?

Yes, on most of the apps above, including Novacrust. Availability of mobile money as a funding method varies by country, so check before you commit to one app.

Do I need a separate wallet, or can I hold USDT in the app itself?

Most of these apps, Novacrust included, let you hold your stablecoins directly in-app rather than requiring a separate wallet. Useful if you want to convert, spend, or send without moving funds around first.

Buy and sell USDT, USDC, and more on Novacrust

Get Started. It’s Free. Then convert your crypto to cash, hold it, or spend it in the same app you already use for your USD Account and money transfers.

How to Buy USDT Safely in 2026: A Complete Guide for Emerging Markets

Search “buy USDT in Malawi” or “how to buy USDT in Maldives” and most of the first page isn’t a licensed exchange. It’s Telegram groups, Facebook posts, and P2P forums where you send money to a stranger first and hope the USDT shows up after. That gap between demand and safe supply is exactly why so many people in Cameroon, Zambia, Nepal, Botswana, and dozens of other markets still buy USDT the hard way.

USDT (Tether) is the most widely used stablecoin in the world, pegged 1:1 to the US dollar. That peg is the whole appeal: your money holds its value in dollars without you needing a US bank account. But “widely used” doesn’t mean “widely available through safe channels” everywhere. This guide covers how USDT actually gets bought and sold, where the real risk sits, and how to buy it in minutes instead of hours.

Why buying USDT is harder than it should be

In markets with limited USD liquidity, mainstream banks, weak local exchange infrastructure, or currency controls, three things usually happen:

  • Local exchanges either don’t exist or don’t support your country
  • Peer-to-peer (P2P) trading fills the gap, which means you’re trusting a stranger, not a platform
  • Rates vary wildly between sellers, and the “cheap” price sometimes hides a scam

None of that is a reason to avoid USDT. It’s a reason to be specific about how you buy it.

How the common USDT scams actually work

Most P2P USDT scams follow the same pattern: a seller offers a rate slightly better than everyone else’s, asks for payment via bank transfer or mobile money first, and then either sends less USDT than agreed, sends it to the wrong network, or disappears entirely. Group admins in Telegram or Facebook communities rarely offer any real recourse once that happens; you’re left with a screenshot and no way to reverse the transfer. This is the exact gap a licensed platform closes: your payment and the USDT release happen inside one system, not across two separate, unconnected steps.

Novacrust vs. P2P groups and other exchanges

Binance P2P, Busha, and Breet.io all let you buy USDT, and each works differently. Binance P2P connects you with individual traders directly, so you’re still trusting a stranger, just inside an app instead of a Telegram group. Busha and Breet.io operate as licensed exchanges in select markets, which is safer than open P2P, but neither pairs USDT buying with a USD Account or virtual card the way Novacrust does. If you want to buy USDT and also hold, spend, or convert dollars from the same wallet, that combination is where Novacrust differs most.

Six rules for buying USDT safely

  1. Use a platform that holds your funds in escrow, not a stranger’s word. If a seller asks you to pay first and “trust the process,” that’s not a platform, that’s a bet.
  2. Check the live rate before you commit. Rates can move within minutes. A platform that locks your rate for a short window protects you from last-second changes.
  3. Confirm the network before you send anything. USDT exists on multiple networks (TRC20, ERC20, and others). Sending to the wrong network address can mean losing your funds permanently.
  4. Avoid sellers who won’t verify their identity. Anonymity on your side is fine. Anonymity on the seller’s side, with no recourse if something goes wrong, isn’t.
  5. Start small the first time. Test any new platform or seller with a small amount before moving your full balance.
  6. Keep your funding trail traceable. Bank transfer or mobile money, not cash handoffs, so you have a record if a dispute comes up.

How to buy USDT on Novacrust

Novacrust lets you buy USDT (along with USDC, BTC, ETH, SOL, and more) directly, with the rate and network shown upfront before you confirm.

  1. Create your account. Sign up in a couple of minutes. No US address or SSN required.
  2. Fund your wallet. Pay via bank transfer, mobile money, or an existing crypto wallet.
  3. Buy USDT at the live rate. The rate you see is the rate you get, with no last-minute markup.
  4. Confirm the network. Novacrust shows you the correct network before you send, so your funds land in the right place the first time.
  5. Hold, spend, or convert. Keep it as USDT, convert to your local currency, or move it into your USD Account.

The whole flow runs on one platform, so there’s no handing money to a stranger and waiting to see what shows up.

Buying USDT in Malawi, Maldives, Cameroon, Zambia, Botswana, and Nepal

Country-specific USDT demand is real, and the friction looks similar everywhere: thin local exchange support, P2P groups filling the gap, and rates that shift depending on who you ask.

  • Malawi and Zambia: Local exchanges are limited, so most buyers rely on P2P sellers found through Telegram or Facebook, often paying via mobile money. A licensed platform removes the guesswork around whether the seller will actually deliver.
  • Maldives: Tourism-driven cash flow means many residents and workers want a stable way to hold dollars without going through a traditional bank. USDT fills that role, but only if the buying process is verified.
  • Cameroon: Mobile money is the dominant payment rail, and USDT buyers here need a platform that accepts it directly rather than routing through a third-party wallet first.
  • Botswana and Nepal: Both have smaller but growing USDT demand, usually from freelancers and remote workers who want to hold part of their income in dollars.

The country changes. The core problem doesn’t: buy from a platform that shows its rate and holds funds securely, not from a stranger’s word.

What buying USDT should actually cost

A fair USDT purchase has two costs: the network fee (small, fixed by the blockchain, not the seller) and the platform’s spread (the difference between the live market rate and what you’re quoted). Watch for sellers who bundle in a third, invisible cost: a marked-up rate disguised as a “discount.” If a rate looks meaningfully better than everyone else’s, ask why before you ask how.

USDT vs. other ways to hold dollars

If your goal is simply holding value in USD, USDT isn’t your only option. A Novacrust USD Account gives you a real US account number in your name, no crypto step required. Some people use both: USDT for speed and portability, a USD Account for a bank-like balance they can receive ACH and wire transfers into. Compare what you actually need before picking one.

FAQ

Is it legal to buy USDT in Malawi, Cameroon, Zambia, Botswana, Nepal, or the Maldives?
Rules vary by country and change over time, so check your local regulations. In most of these markets, buying and holding USDT through a licensed platform is legal; the risk is usually with unregulated P2P sellers, not the asset itself.

How long does it take to buy USDT?
On Novacrust, a purchase completes in minutes once your wallet is funded. P2P trades can take much longer, since you’re waiting on another person to respond and confirm.

Can I buy USDT with mobile money?
Yes, on Novacrust you can fund your wallet with mobile money in supported countries and buy USDT directly from that balance.

Is USDT the same as a US dollar?
No. USDT is a stablecoin designed to track the US dollar’s value 1:1, but it’s a crypto asset, not a bank deposit. It moves like crypto and settles fast, which is the main reason people use it instead of, or alongside, traditional banking.

What’s the minimum amount of USDT I can buy?
This depends on the platform. Novacrust supports small first purchases, so you can test the process before committing a larger amount.

Buy USDT without the guesswork

You shouldn’t have to trust a stranger’s screenshot to hold dollars. Buy USDT on Novacrust with a live rate, a verified network, and funds that move in minutes, not hours.

Get Started. It’s Free.

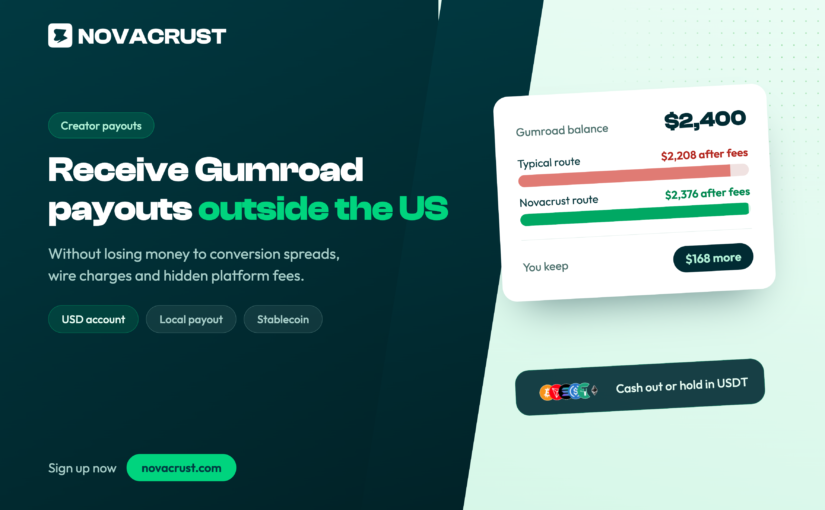
How to Receive Gumroad Payouts Outside the US (Without Losing Money to Fees)

Gumroad does not let you add a payout method if your country is not on its supported list, and that list leaves out most of Africa, plus large parts of Asia and Latin America. Creators in Nigeria, Kenya, Ghana, Pakistan, and dozens of other countries hit the same wall: sales pile up in their Gumroad balance with nowhere to send them.

The usual workaround, routing payouts through a US-based friend’s PayPal or a forwarding service, costs 3 to 8 percent in fees and conversion spread on every payout. On a $500 month, that is $15 to $40 gone before the money even reaches you.

Why Gumroad payouts fail for so many creators

Per Gumroad’s own payout documentation, Gumroad pays out two ways: PayPal, or direct deposit to a US bank account. PayPal is only available in a limited set of countries, and even where it works, PayPal’s own conversion rates run 3 to 4 percent above the mid-market rate. Direct deposit needs a real US bank account with a routing and account number, which is exactly what most creators outside the US do not have.

That second option, direct deposit, is actually the cheaper and faster path. You just need the US account to plug into it.

The fix: a USD Account with a real routing number

A Novacrust USD Account gives you a US account number and routing number you can add directly to Gumroad’s payout settings, the same way a creator living in Ohio would. Gumroad pays out via ACH straight into your account. No PayPal, no forwarding service, no friend holding your money. If you want the mechanics of how ACH payouts actually work, see ACH vs Wire vs SWIFT.

Here is the setup:

  1. Create a Novacrust account and open a USD Account. It takes minutes and needs no US address or Social Security number.
  2. Copy your account and routing number from your Novacrust dashboard.
  3. In Gumroad, go to Settings, then Payments, and add your Novacrust USD Account as a bank payout method.
  4. Set your payout schedule. Gumroad sends funds via ACH, which typically lands in 1 to 3 business days.

Once your dollars land, spend them with a Novacrust USD Virtual Card, convert to naira, cedis, shillings, or another local currency at competitive rates, or send to 50+ countries. You keep the payout in dollars for as long as you want and move it only when you are ready.

It is not just Gumroad

The same routing and account number works for any platform that pays out via US direct deposit or ACH: Upwork, Fiverr, Patreon, Payhip, Podia, and most US-based marketplaces and ad networks. Set it up once on your Novacrust USD Account, and you can add it as a payout method everywhere you get paid. This is the same setup covered in our guide to the US banking system for non-residents, if you want the fuller picture of how a US account number works without a US address.

This is the difference between chasing a payout workaround for every platform and having one dollar account that plugs into all of them.

What this actually saves you

A creator earning $800 a month through Gumroad, routing payouts through PayPal or a forwarding service at a 5 percent blended cost, loses about $40 a month, or $480 a year. Routing the same $800 through a USD Account cuts that to Novacrust’s standard conversion rate, only charged when you actually convert to local currency, and only on the portion you convert.

FAQ

Can I add a Novacrust USD Account to Gumroad if I do not live in the US?
Yes. The USD Account comes with a real US account and routing number that works in Gumroad’s bank payout settings regardless of where you live.

How long does a Gumroad payout take once I switch to direct deposit?
Gumroad sends ACH payouts on your chosen schedule, and funds typically arrive in your Novacrust USD Account within 1 to 3 business days.

Do I need a US address or Social Security number to open a USD Account?
No. Novacrust’s USD Account is built for freelancers and creators outside the US and does not require either.

Can I use the same USD Account for Upwork, Fiverr, or Patreon payouts?
Yes. Any platform that supports US bank direct deposit or ACH can pay out to the same Novacrust USD Account.

What can I do with the dollars once they land?
Hold them in USD, spend them with a Novacrust USD Virtual Card, convert to your local currency at competitive rates, or send to 50+ countries.

Stop losing 5 percent of every Gumroad payout to a workaround. Get Started. It’s Free. Open your Novacrust USD Account in minutes and add it as your payout method today.

How to Send Money to Ethiopia From Abroad (2026 Guide)

The World Bank’s Remittance Prices Worldwide data puts the average cost of sending money to Sub-Saharan Africa at over 7 percent of the transfer, among the highest remittance fees anywhere in the world. Send $500 to Ethiopia through the wrong channel and $35 or more never reaches your recipient. It disappears into a wire fee, a bad exchange rate, or both.

Ethiopia adds its own wrinkle: birr access is tightly controlled, and not every international transfer service pays out directly to a bank account or Telebirr wallet inside the country. This guide covers what actually determines the cost of sending money to Ethiopia, which payout method gets your recipient paid fastest, and how the process works on Novacrust.

Why Sending Money to Ethiopia Costs More Than It Should

Three things drive up the cost of a transfer to Ethiopia specifically: a marked-up exchange rate instead of the real one, a payout network that routes through a correspondent bank before it reaches Ethiopia, and a fee structure that hides part of its cut inside the rate instead of the receipt.

Traditional bank wires are usually the worst offender. A wire from a US or UK bank to Ethiopia can take 3 to 5 business days and cost $25 to $45 in fees before the exchange rate markup is even factored in. Western Union and similar cash-pickup services move faster, but the rate they quote is rarely the mid-market rate, and that gap is where a chunk of your money goes. For a broader look at how transfer costs stack up across methods, see our guide to the best way to send money internationally.

Five Rules for Sending Money to Ethiopia Without Losing Value

  1. Check the live exchange rate before you send. A transfer that looks cheap on fees alone can still cost more than a competitor with a better birr rate. Compare the total amount your recipient gets, not the fee line item.
  2. Confirm the payout method before you commit. Bank deposit to Commercial Bank of Ethiopia, Awash, or Dashen works for most recipients. Telebirr mobile money is faster for recipients without a bank account nearby.
  3. Avoid services that route through multiple correspondent banks. Every extra bank in the chain adds a day and a fee. A platform that pays out directly moves faster and costs less. This is the same routing problem we cover in ACH vs Wire vs SWIFT.
  4. Send in local currency terms your recipient understands. Confirm the birr amount landing on their end, not just the dollar or pound amount you’re sending.
  5. Keep the confirmation. A transfer reference number and payout confirmation are the only things that help if a transfer is delayed on the Ethiopian side.

How to Send Money to Ethiopia on Novacrust in 4 Steps

Step 1: Sign in and select your destination

Sign in to your novacrust.com account, tap Send Money, and choose Ethiopia from the list of 50+ supported countries.

Step 2: Choose bank deposit or Telebirr

Enter your recipient’s bank details or Telebirr mobile number. Both payout options are supported.

Step 3: Confirm the rate and amount

Novacrust shows you the exact birr amount your recipient gets, at the live rate, before you confirm anything.

Step 4: Send

Once you confirm, the transfer is on its way. Most transfers to Ethiopia land within minutes, not days.

Novacrust vs Other Ways to Send Money to Ethiopia

Bank wire Western Union Novacrust
Speed 3-5 business days Minutes to hours for cash pickup Minutes, straight to bank or Telebirr
Rate visibility Often unclear until it lands Marked-up rate, shown late Live rate shown before you send
Fees $25-$45 plus markup Flat fee plus rate markup Transparent fee, shown upfront
Payout options Bank only Mostly cash pickup Bank deposit or Telebirr

Lemfi is a reasonable option for sending to Ethiopia too, with its own dedicated transfer corridor. What changes the decision is what else you can do with your money afterward. On Novacrust, the same account handles crypto, a USD Account, Gift Cards, and a virtual dollar card, not just this one transfer corridor.

Frequently Asked Questions

How long does it take to send money to Ethiopia?
On Novacrust, most transfers land within minutes. A traditional bank wire can take 3 to 5 business days.

Can I send money to a Telebirr wallet directly?
Yes. Novacrust supports payout directly to Telebirr, alongside bank deposit to major Ethiopian banks.

What’s the cheapest way to send money to Ethiopia?
The cheapest option is the one where the total birr amount landing with your recipient is highest, after fees and exchange rate. Always compare that number directly, not just the advertised fee.

Do I need a Telebirr account or Ethiopian bank account to receive money?
Your recipient needs either a Telebirr wallet or an account at a supported Ethiopian bank. Novacrust pays out to both.

The Bottom Line

Sending money to Ethiopia doesn’t have to cost 7 percent of every transfer or take a week to land. A platform that shows you the real rate upfront and pays out directly to a bank account or Telebirr wallet gets your money there faster, for less.

Send money to Ethiopia on Novacrust. Get Started. It’s Free.

Money Management for Remote Workers and Digital Nomads: The Complete 2026 Guide

You sent the invoice three weeks ago. The client confirmed payment days ago. And yet your money is still floating somewhere between a foreign bank, an intermediary you have never heard of, and an exchange rate that quietly shaved off a chunk you will never get back. If you earn a living online and get paid from abroad, you know this feeling. The work is the easy part. Getting paid, keeping the value of what you earned, and spending it is where the real friction lives.

Money management for remote workers is not about budgeting apps or colour-coded spreadsheets. It is about something more basic: getting your money in quickly, holding it in the currency you earned, spending it anywhere, and moving it home at a fair rate, without losing time or money at every step. This guide covers how to get paid as a remote worker in 2026, how to keep more of what you earn, and how to choose a platform that handles the whole journey instead of forcing you to stitch five tools together.

Why money management for remote workers is harder than it looks

When you work for a local employer, money is simple. The salary lands in your local bank, in your local currency, and you spend it locally. Remote work breaks that loop.

Now your international clients might be in New York, your bank in Lagos or Cairo or London, your subscriptions billed in dollars, and your rent due in a currency none of those clients use. Every handoff between currencies and countries is a chance to lose money to fees, time to slow transfers, or value to a poor rate. Multiply that by every invoice, and the leak becomes a flood. The people who keep the most of what they earn are not the ones who hustle the hardest. They are the ones who fixed their setup once and stopped bleeding value on autopilot.

The four jobs your money setup needs to do

A strong setup does exactly four things: receive, hold, spend, and send money from one platform, instead of logging into a different service for each.

1. Receive international payments without the wait

Many remote workers still rely on slow transfers that pass through several banks, take five to seven working days, and arrive lighter because each bank took a cut. If you have ever searched for how to get paid as a freelancer with overseas clients, this is the problem you were trying to solve.

What you want is a multi-currency account for freelancers, a foreign currency account in your own name, that lets you receive dollars, pounds, or euros through familiar rails like ACH and wire transfer, so your international clients can pay you the way they pay anyone else. When a client can pay you with no extra effort, you get paid faster and look more professional doing it.

2. Hold your money in the currency you earned

Here is a costly mistake. You earn in dollars, the money lands, and it gets force converted into your local currency on arrival. Next week, you need dollars again for software or ads, so you convert back, losing a slice each way.

A proper setup lets you hold foreign currency as foreign currency. If your next expense is in dollars, the money should never detour through your local currency and back. Holding multiple currencies in one place means you convert only when you choose, at a moment you choose.

3. Spend globally without your card getting declined

You found the perfect setup, the money is in, and then your card is declined for a tool you need for work. Anyone paying for international subscriptions from outside the US or Europe has lived this. Local cards get rejected by global merchants constantly, and the ones that work often carry painful limits.

This is where a virtual dollar card changes your day-to-day life. A good one pays for the services you actually use, from streaming to design tools to advertising platforms, and lets you fund it from local currency, your dollar balance, or crypto you convert on the spot. No foreign bank account required, with limits high enough that you are not topping up every hour.

4. Convert and send money home at a fair rate

Eventually, you need some of that income in your local currency, for rent, for family, for life. Many platforms advertise zero fees and then bake their profit into a rate that sits well below the real market rate. You feel good about the no-fee headline while losing more than a fee ever would have cost you.

What you want is a transparent rate close to the real mid-market rate, so you see exactly what you get before you confirm. A fair rate on every conversion, across a year of income, is the difference between keeping your money and donating it to a spread you never agreed to.

Digital nomad banking: what changes when you move

If you are moving between countries, the stakes climb. Digital nomad banking has its own quirks. Your home bank may freeze a card it sees used in three countries in a month. Opening a local account in each new country is slow and often impossible on a tourist or nomad visa, which is why a traditional bank account for digital nomads is so hard to keep.

The countries courting nomads, the UAE chief among them, with its digital nomad visa, have pulled in a wave of location-independent earners and expats facing one question: how do I manage money without permanent residency anywhere? The answer is a digital nomad bank account that travels with you, holds multiple currencies, issues a card that works across borders, and does not panic when your spending map looks like a flight route. Sorting out your digital nomad visa finances before you land somewhere new saves you the scramble of fixing it once you are already abroad.

The mistakes that quietly cost remote workers the most

Four patterns show up again and again, and each is avoidable. The first is juggling too many tools, where every handoff costs a fee and a delay. The second is ignoring the exchange rate because the platform said “no fees,” when the rate is the fee. The third is force converting the income you will need again into the same currency. The fourth is staying with a slow, traditional channel out of habit. Changing is a one-time cost. The savings repeat every month for as long as you work.

How to choose the best fintech platform for remote workers

Judge each option against the four jobs. Run through this list:

  • Can you receive USD, GBP, and EUR into a foreign currency account in your own name, using ACH and wire transfer?
  • Can you hold more than one currency and convert only when you choose?
  • Does it issue a virtual dollar card that works with global merchants, with real limits?
  • Is the exchange rate transparent and close to the real market rate?
  • Does it cover the countries and corridors you actually live and work in, not just one market?

The best fintech platform for remote workers answers yes to all five, because that is the one that lets you stop managing money and get back to your work.

Bringing it together: one platform instead of five

This is the gap Novacrust was built to close. Instead of one tool to receive, another to hold, a third to spend, and a fourth to send, it brings the whole journey into a single platform. You can receive international payments through a USD account in your name with ACH and wire support, hold and manage multiple currencies, spend worldwide on a virtual dollar card you fund from local currency, dollars, or crypto you convert in app, and send money home at a transparent rate. For creators, freelancers, and remote workers tired of watching income leak across half a dozen services, that consolidation is the entire point.

Frequently asked questions

What is the best way to manage money as a remote worker?

Build your setup around four jobs: receiving payments, holding your money in the currency you earned, spending globally, and converting or sending money home at a fair rate. The fewer tools involved, the less you lose to fees and delays.

How do remote workers get paid by international clients?

The most reliable approach is a multi-currency account in your own name that supports ACH and wire transfers, so clients can pay you using rails they already know. This is faster than slow transfers that pass through several banks.

What is the best app to receive money from abroad?

Look past the label and judge on substance. The best option lets you receive money from abroad into an account in your own name, hold it in the currency you earned, spend it on a global card, and convert it at a transparent rate, all in one place. A platform that does the full journey beats a single-feature tool every time.

Do I need a foreign bank account to manage money as a digital nomad?

No. Modern platforms give you a digital nomad bank account that holds multiple currencies, receives international payments, and spends on a virtual card without opening a local bank account in each country.

How can I avoid losing money on currency conversion?

Hold foreign currency as foreign currency and convert only when you choose. Always compare the platform’s rate to the real market rate, because a “no fees” claim often hides its cost inside a poor exchange rate.

ACH vs Wire vs SWIFT: Which Should You Use to Get Paid From Abroad?

Mary closed her biggest design contract yet, a US client paying four figures a month. She invoiced, the client paid the same day, and she spent the week feeling like a professional who had finally made it. Then she waited. Six days later, the money landed, except it was short by $40 she could not explain, skimmed by a bank she had never agreed to deal with. The work had gone perfectly. The getting paid part was a mess, and nobody had ever taught her the difference between the options her client kept asking about.

That gap is what this guide closes. ACH, wire transfer, and SWIFT are the three ways most international payments move, and the difference between them is real money and real days. Understanding the ACH vs wire transfer question, and where SWIFT fits in, means you can tell a client exactly how to pay you, get your money faster, and stop losing a cut to fees you never needed to pay.

The short answer first

 ACHWire transferSWIFT
Best forRoutine US paymentsLarge or urgent paymentsPayments across borders
Speed1 to 3 business daysSame day to 1 day domestically1 to 5 business days
CostLow or freeHigher fixed feeHigher, often with intermediary fees
ReachWithin the USDomestic and internationalGlobal, bank-to-bank worldwide

If your client is in the US and the payment is routine, ACH is usually cheapest. If the payment is large or urgent, a wire is faster and more certain. If the money is crossing borders, SWIFT is the network doing the work behind the scenes. Now, let us make each one make sense.

What is an ACH payment?

ACH stands for Automated Clearing House. It is the network that moves money between banks inside the United States. If you have ever had a US salary deposited automatically, paid a US bill online, or received a refund into a US account, ACH did the work.

The appeal of ACH is cost. It is cheap, often free, which is why it is the default for recurring and everyday payments in the US. The trade-off is speed and reach. An ACH payment usually takes one to three business days to settle, and it only works within the US banking system. So if a US client is paying you and you hold a US-style account, ACH is the low-cost, no drama option for regular invoices.

How long does ACH take?

Most ACH payments clear in one to three business days. Some processes are same-day if the sender uses faster ACH options, but plan around the standard window. ACH does not move on weekends or US bank holidays, so a payment sent on a Friday may not land until the middle of the following week.

What is a wire transfer?

A wire transfer is a direct, bank-to-bank movement of money. Instead of being batched and processed in groups like ACH, a wire is sent individually and tends to settle much faster, often the same day for domestic transfers.

Wires are the tool of choice when speed and certainty matter, for example, a large project payment, a deposit, or anything where both sides want confirmation that the money has truly moved. The cost is the catch. Wires usually carry a fixed fee on the sending side, and sometimes on the receiving side too. For a small invoice, that fee feels heavy, but for a large or time-sensitive payment, the speed is worth it. To receive a wire transfer, you give the sender your account details and a routing number or equivalent, plus a few extra pieces of information for international wires.

What is SWIFT?

SWIFT is not a payment in the way ACH and a wire are. It is the messaging network banks around the world use to talk to each other and instruct international transfers. When money moves between a bank in one country and a bank in another, a SWIFT message usually coordinates it. This is why an international wire is often called a “SWIFT transfer.”

The strength of SWIFT is global reach. It connects thousands of banks worldwide, which is how a client in one country can pay a freelancer in another at all. The weakness is what happens along the way. An international SWIFT transfer can pass through one or more intermediary banks, and each can take a fee and add a day. This is the mystery slice that goes missing between the invoice amount and what finally lands in your account. It is exactly what cost Mary her forty dollars.

ACH vs wire vs SWIFT: the differences that affect you

Speed, cost, and reach are the three levers. ACH wins on cost but is slow and US only. A wire wins on speed and certainty but costs more per transfer. SWIFT is what makes an international wire transfer possible at all, with the widest reach but the highest chance of intermediary bank fees and delays.

For most freelancers, the practical reality looks like this. A US client paying a routine invoice reaches for ACH because it is cheap and easy on their end. A client sending a large payment, or one who wants it to land fast, uses a wire. And the moment that money travels from one country to another, SWIFT carries it, with the extra cost and time international hops add.

Which should you use when?

A few simple scenarios cover most situations:

  • Your client is in the US, and the invoice is routine. Ask for ACH. It is the cheapest and most reliable for regular work.
  • The payment is large, or you need it quickly and confirmed. Ask for a wire. The fee is worth the speed.
  • You and your client are in different countries. The payment travels over SWIFT, so build in a few extra days and expect possible intermediary fees.
  • You want the smoothest experience over time. Set yourself up to accept both ACH and wire, so a client can pay you the way that suits them rather than the way you are stuck with.

The catch for anyone outside the US

Here is the part most guides skip. ACH and US-style wires assume you have an account that can receive them, with a real account number and routing number in your name. For people living outside the US, that has long been the hard part. You can know everything about how to receive a wire transfer and still have nowhere for the money to land.

This is the gap modern financial platforms close. With a USD account in your own name that supports both ACH and wire transfers, you can hand a US client your details and let them pay you exactly as they would pay anyone local. Novacrust offers this kind of account, so you can receive international payments through familiar rails, hold the dollars you earn, and convert or spend them on your own terms rather than losing value the moment the money arrives. Once you have the right account, the ACH vs wire decision stops being a source of anxiety and becomes a quick, informed choice you make to get paid faster and keep more of what you earned. Mary switched to one after that first short payment, and her next invoice landed whole.

Frequently asked questions

What is the difference between an ACH and a wire transfer?

ACH moves money between US banks in batches, which makes it cheap but slower, usually one to three business days, and limited to the US. A wire transfer is sent individually and settles much faster, often the same day domestically, but carries a higher fee. ACH suits routine payments, and wires suit large or urgent ones.

Is SWIFT the same as a wire transfer?

Not exactly. A wire is the transfer itself, while SWIFT is the global messaging network banks use to coordinate international wires. An international wire usually travels over SWIFT, which is why the terms get used together.

How long does ACH take to arrive?

Typically, one to three business days. ACH does not process on weekends or US bank holidays, so timing depends on when the payment is sent.

Which is cheapest for receiving international payments?

ACH is usually cheapest when it is available, but it only works within the US. For payments across borders, you are often dealing with a SWIFT-based wire, where the key is an account that minimises intermediary bank fees and gives you a fair conversion rate once the money lands.

Keep reading

  • Money Management for Remote Workers and Digital Nomads: The Complete 2026 Guide

Kali Kimanzi: What It Really Takes to Work with International Clients from Africa

You can be the most talented developer in your country. You can win innovation awards. You can land international clients. And still lose opportunities not because you’re not good enough, but because they simply can’t pay you.

Kali Kimanzi knows this reality too well. As someone who’s navigated the gap between African innovation and European optimization, who’s registered businesses on two continents, and who’s watched transaction fees eat into hard-earned payments, he’s learned that talent without access is just potential waiting to be unlocked.

In this conversation, Kali shares what nobody posts on LinkedIn: the rejections, the waiting, the payment nightmares, and the unglamorous truth about building a global career from Africa.

Can you briefly introduce yourself and tell us what you do?

My name is Kali Kimanzi. I’m the CTO and Co-founder of CodeX Safari, and I also serve as the CEO.

At CodeX Safari, we build technical solutions both hardware and software for businesses, governments, and NGOs. We also develop internal products that help businesses manage their operations more efficiently.

One of our key products is Codex POS Store, which is an inventory and point-of-sale platform.

Currently, we work with clients across Kenya and internationally, including the United States, as we are incorporated both in Kenya and in Wyoming, USA.

How did your journey into the digital or creative space begin?

My journey began during my university days. My background is in Mathematics and Computer Science.

In 2019, I went to Austria to pursue my Master’s degree in Computer Science. During that time, I got my first experience working in the digital space within a larger company.

Over time, I started comparing what was happening in Europe and Africa. Europe is more focused on optimization improving existing systems while Africa is still in the innovation stage, where there are many problems to solve.

I saw bigger opportunities in Africa, especially in Nairobi. That’s what led me to start my company and eventually return in 2022 to focus on building it fully.

What first inspired you to start building your career online?

For me, it has always been about solving problems.

From high school, I was involved in innovation programs where we created solutions for societal challenges. In university, I was recognized among the top innovators in the country for a water management system I digitized using IoT devices.

That experience showed me there is a huge gap where technology can improve systems and make life more efficient.

So my inspiration has always been to build solutions that automate processes and improve how society functions.

What were some of the biggest challenges you faced when you were just starting out?

One of the biggest challenges was not just building solutions, but getting people to adopt them.

Many businesses across Africa are not yet fully digital. A large number of business owners belong to older generations Gen X and baby boomers who are not as quick to adopt new technology.

So even when we had strong solutions, it took time for them to understand the value:

  • How it improves their business
  • How it makes operations easier
  • Why they should trust it

Adoption has been one of the biggest challenges, because building a solution is one thing, getting people to trust and use it is another.

Did you ever face issues receiving payments from international clients? How did that impact your growth?

Yes, receiving payments was very difficult in the beginning.

There were high transaction fees, especially with platforms like PayPal. You could receive $500 and lose a significant portion to fees and conversion charges.

This affected growth because even when you had clients, accessing your money wasn’t always smooth.

What was your very first international payment experience like?

It involved a lot of waiting.

On paypal, SWIFT transfers were supposed to take about 4 to 5 days, but in reality, it could take a week and a half or even two weeks.

So most of the time, I just waited for days, hoping the payment would come through.

How did you handle the payment challenges at the time?

I adjusted and adapted.

There weren’t many options, so I learned to be patient and plan around delays.

In your opinion, how important is having a reliable dollar payment account for freelancers and digital creators?

It’s like oxygen for freelancers.

Without a reliable way to receive payments, you miss out on opportunities not because you lack skills, but because clients cannot pay you easily.

Was there a particular moment or opportunity that really changed things for you?

Yes.

At one point, I had to register a business in the United States just to be able to receive payments properly. That meant paying taxes both in Wyoming and in Kenya, which wasn’t ideal.

But it became a breakthrough moment because it allowed us to operate internationally and receive payments more reliably.

What skills or mindset helped you grow the most in your career?

Networking and continuous learning.

You can be highly skilled, but if you don’t network, opportunities won’t find you. Most of the projects I’ve worked on came through connections, conversations, and referrals.

What lessons would you share with African freelancers looking to work with global clients today?

Trust and reliability are everything.

When clients trust you and you deliver consistently and on time, they don’t just come back, they refer you.

Growth often comes from referrals, and over time, that builds into something much bigger.

How do you stay consistent and motivated even during slow or challenging periods?

I remind myself that I’m not alone.

I talk to other entrepreneurs, and I’ve realized that everyone faces challenges, even if they are different.

That helped me understand that business is about challenges, it’s how you respond to them that matters.

What is one honest truth about building a global career that nobody tells young African creators and freelancers?

There will be a lot of rejection.

You might face hundreds or even thousands of rejections, but that’s part of the process.

People only show success online, they don’t show how many times they failed before getting there.

Platforms like Novacrust are trying to make international payments easier for freelancers. What are your thoughts on solutions like this?

Solutions like this are very important because they bring inclusion.

Without access to global payment systems, you’re excluded from opportunities—not because you lack skills, but because you can’t get paid.

But when that barrier is removed, you can offer your services globally and access more opportunities.

Would you consider signing up for a platform like Novacrust? Why or why not?

Yes, I would and I already have.

Because I understand what it means to have access to a system that makes payments easier.

Being able to receive money and move it into local systems like mobile payments is very important, especially in Africa.

Kali’s journey highlights a key reality: talent alone is not enough. Access, systems, and persistence play a major role in building a global career.

From navigating payment barriers to building innovative solutions, his story shows that success comes from consistency, adaptability, and resilience.

For African freelancers and creators, the opportunity is global but unlocking it requires the right tools, mindset, and determination.

Which App Gives the Best USD to Naira Exchange Rate?

You received $500 from a client. By the time it hits your Nigerian bank account, it feels like you lost money without spending anything.

This is why thousands of freelancers and remote workers keep searching:

  • best usd to naira rate app
  • exchange usd to naira online
  • wise vs payoneer rate
  • grey rate today

The real problem is not getting paid in dollars. The real problem is how much of those dollars you keep after conversion.

Many African freelancers now use Novacrust because it allows them to receive USD, convert at competitive rates, and withdraw to their bank without the silent losses that happen across multiple platforms.

This guide breaks down how the most popular apps handle USD to NGN conversion and what actually gives you the best value.

Why USD to Naira conversion is where freelancers lose money

Most freelancers focus on receiving USD from clients. Very few pay attention to what happens during conversion.

Losses usually happen through:

  • Hidden exchange rate margins
  • Multiple conversion steps
  • Transfer and withdrawal fees
  • Delays that force you to convert at bad rates

This is why people keep comparing wise vs payoneer rate and checking grey rate today before converting.

How conversion typically works with popular platforms

Freelancers often receive USD using:

Each platform allows conversion, but the final naira amount you receive can differ significantly because of rate margins and processing structure.

What determines the amount you receive in naira

Your final payout depends on:

  1. The platform’s internal exchange rate
  2. Additional conversion or withdrawal charges
  3. Time delays before funds hit your bank
  4. Extra steps between USD wallet and local account

Even a small difference in rate becomes large when you convert hundreds or thousands of dollars monthly.

Example: Converting 1000 USD to Naira

Let us assume the market rate is 1500 NGN per dollar.

PlatformEffective Rate You GetNaira Received
WiseSlightly below marketLower payout
PayoneerIncludes marginLower payout
GreyCloser to marketBetter payout
NovacrustCompetitive rateHigher payout

This is why freelancers constantly search best usd to naira rate app before converting.

Why many freelancers now convert USD using Novacrust

Novacrust removes the long chain between receiving USD and converting to naira.

You can:

  • Receive USD directly
  • Convert at competitive rates inside the same platform
  • Withdraw to your Nigerian bank quickly

There are no multiple apps reducing your earnings at each step. This is what makes a real difference over time.

The mistake most freelancers make

They choose a platform based on how easy it is to receive USD, not how well it converts USD to NGN.

The real money is saved at the conversion stage, not the receiving stage.

How to choose the best app to exchange USD to Naira online

Look for a platform that:

  • Shows transparent rates
  • Minimizes steps between USD and NGN
  • Allows fast withdrawal to your bank
  • Is built with African freelancers in mind

This is where many traditional platforms fall short.

Final thoughts

Getting paid in dollars is only half the journey. Converting those dollars at a good rate is what protects your income.

The difference between platforms may look small per transaction, but over months of freelance work, it becomes significant.

Choosing the right app for USD to naira conversion is how you stop losing money silently.

Sign up to get started on Novacrust here.