What a Navy Federal International Wire Transfer Actually Costs in 2026

$25. That is what Navy Federal charges you to send an international wire, and the money can still take up to 7 business days to land, sometimes with less showing up on the other end than you sent.

Navy Federal is one of the largest credit unions in the country, and thousands of its members search for the same thing every month: how to actually send a wire abroad, what it costs, and how long it takes. The answers are not hidden, but they are not exactly convenient either. Here is what Navy Federal actually charges, how the process works, and a faster way to move the same money.

What a Navy Federal wire actually costs

According to Navy Federal’s own fee schedule, the breakdown is simple:

  • Domestic outgoing wire: $20
  • International outgoing wire: $25
  • Incoming wire (domestic or international): $0

That $25 only covers what Navy Federal itself charges. It does not cover what happens once your money leaves the credit union. International wires typically pass through one or more correspondent banks before reaching the recipient’s account, and each one can take a small cut along the way. That is a big part of why a wire often arrives short of what you actually sent, and it is true whether you bank with Navy Federal, Chase, or almost anyone else moving money the traditional way.

How long it actually takes

Navy Federal states that domestic wires post within 1 to 2 business days, while international wires take 5 to 7 business days. Incoming wires are processed the same day if received before 6:30 pm ET.

A week is a long time to wait when someone overseas is counting on that money for rent, tuition, or an emergency. If timing matters more than the $25 fee, it is worth comparing wire against the other transfer options before you commit. Novacrust’s breakdown of ACH, wire, and SWIFT walks through when each one actually makes sense.

How to actually send one

Unlike most digital-first banks and fintech apps, Navy Federal does not let you initiate an international wire entirely on your own through online banking. You have four options:

  1. Send a secure message through mobile or online banking
  2. Call 1-888-842-6328 and request it by phone
  3. Visit a branch, and confirm ahead of time that it offers international wire services, since not every branch does
  4. Mail a completed International Transfer Request Form to Navy Federal’s Funds Disbursement Section in Vienna, Virginia

Every route requires you to fill out an International Transfer Request Form with the recipient’s bank details, SWIFT code, and correspondent bank information if the receiving bank needs one. None of it happens with a couple of taps on your phone.

Is there a limit on how much you can wire?

Navy Federal does not publish a fixed dollar limit for wire transfers on its website. In practice, that usually means larger transfers get extra scrutiny rather than an automatic cap: expect additional identity checks or a request to confirm the transfer by phone or in person once the amount gets large. If you are planning to move a significant sum, call Navy Federal directly before you try to send it, so you are not caught off guard mid-transfer.

What about a virtual card number?

Navy Federal does not market a standalone virtual card number the way some digital banks do. Its debit and credit cards work with Apple Pay, Google Pay, and Samsung Pay for tap-to-pay purchases, but there is no separate, disposable card number generated on demand for online checkout. If that is specifically what you are after, a USD Virtual Card built for online spending will get you closer to what you are picturing.

A faster way to move the same money

$25 and up to a week is the cost of using the traditional wire system, and federal rules exist specifically because that system has historically hidden its true price from consumers. The Consumer Financial Protection Bureau’s remittance transfer rule requires many providers sending international transfers to disclose the exact exchange rate and fees before you send, precisely because that information used to be buried or missing entirely.

Novacrust skips the branch visits, the mailed forms, and the multi-day wait. Send money to 50+ countries in seconds, with the rate and fee shown upfront before you confirm anything. If a Navy Federal wire is only part of your routine because it is the option you already know, it is worth comparing it against what else is out there.

FAQ

Does Navy Federal charge to receive an international wire?
No. Navy Federal does not charge a fee to receive a wire, domestic or international. The sending bank or a correspondent bank in between may still take a cut before the money reaches your account.

How long does a Navy Federal international wire take?
Navy Federal states 5 to 7 business days for outgoing international wires, compared to 1 to 2 business days for domestic wires.

Can I send a Navy Federal wire entirely online?
Not fully. You can start the request through a secure message in online or mobile banking, but Navy Federal also requires a completed International Transfer Request Form, and some members choose to call or visit a branch instead.

Is there a maximum amount I can wire from Navy Federal?
Navy Federal has not published a fixed limit. Larger transfers are more likely to trigger extra verification, so call ahead if you are sending a significant amount.

Does Navy Federal offer a virtual card number for online purchases?
No. Navy Federal’s cards support mobile wallets like Apple Pay and Google Pay, but there is no separate on-demand virtual card number the way some digital-first banks offer.

Sign up to get started on Novacrust here.
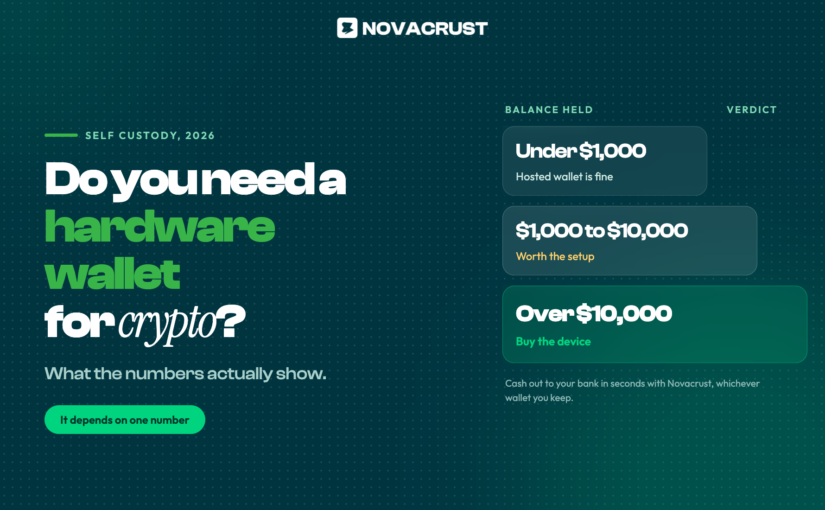
Do You Need a Hardware Wallet for Crypto? What the Numbers Actually Show (2026)

Crypto hacks and scams cost people more than $2.37 billion in the first six months of 2025 alone, a 66% jump from the year before. That number is usually the moment someone starts googling “hardware wallet,” convinced that a $70 USB stick is the only thing standing between them and disaster. It helps, but not in the way most buyers think, and it comes with a tradeoff nobody puts on the box.

What a hardware wallet actually protects you from

A hardware wallet is a small physical device that stores your private keys offline and signs transactions without ever exposing those keys to the internet. Even if your phone or laptop is compromised with malware, the keys never leave the device. That’s the whole pitch, and it’s a real one.

The numbers back it up. Wallets that use hardware key storage with air-gapped signing report incident rates under 5%. Software-only wallets, the kind that live entirely as an app on your phone, sit above 15%. If your threat model is “malware on my device” or “a phishing site tricking me into signing something,” a hardware wallet closes that gap better than almost anything else available.

The tradeoff nobody mentions

Here’s the part the marketing skips: hardware wallets don’t reduce risk, they relocate it. Instead of trusting a company to protect your funds, you’re trusting yourself to never lose a 12 to 24 word recovery phrase, never damage the device beyond recovery, and never mix up which piece of paper it’s written on.

That risk is not hypothetical. Chainalysis estimates that somewhere between 2.3 million and 3.7 million Bitcoin, roughly 11 to 18% of the entire fixed supply, is permanently lost. Not stolen: lost. Forgotten passwords, discarded hard drives, seed phrases nobody could find again. There’s no customer support line for a lost recovery phrase. If it’s gone, the funds are gone with it.

So who actually needs one?

A hardware wallet earns its cost and hassle for a specific kind of user:

  • You’re holding a large amount long term. If you’re not touching the funds for months or years, the inconvenience of a hardware device matters less than the security upgrade.
  • You’re comfortable being your own bank. No support desk, no password reset, no fraud department. If your phone breaks and your seed phrase is also gone, that’s the whole story.
  • You already understand wallet security basics. Our breakdown of custodial versus non-custodial wallets is worth reading first if any of this is new.

For everyone else, especially people buying and selling USDT or USDC regularly to move money, pay for something, or convert to local currency, a hardware wallet adds friction without adding much practical protection. You’d still need to plug it in, confirm each transaction on a small screen, and manage a recovery phrase for funds that don’t sit still long enough to benefit from cold storage.

The middle ground most people actually want

Most of the “hardware wallet or nothing” framing skips the option in between: a custodial platform that handles key security on its own infrastructure while you keep control of when and where your money moves. You lose the do-it-yourself independence, but you also lose the single point of failure that a lost seed phrase represents. There’s no recovery phrase to misplace because there’s no recovery phrase in your hands at all.

That’s the tradeoff worth making for anyone using crypto as a way to receive, hold briefly, and move money rather than as a long-term vault. If you’re new to buying USDT this way, our guide to buying USDT safely covers the basics, and if you’re specifically weighing options while living somewhere without a local exchange, this FAQ on crypto wallet safety in emerging markets answers the questions that come up most.

How to decide in under a minute

Ask yourself three questions:

  1. Am I holding this for years, or moving it within days or weeks?
  2. Would I rather manage my own recovery phrase, or never have one to lose?
  3. Is my main risk a hacked device, or a lost one?

Long-term holder worried about hacks: get a hardware wallet. Everyone else, especially anyone using crypto to send, receive, or convert money regularly: a well-secured custodial platform removes the seed phrase risk entirely, which for most people is the bigger danger day to day.

You can buy and sell USDT, USDC, BTC, ETH, SOL, and more directly on Novacrust without ever generating a seed phrase to lose. See how it works for crypto buyers in Nigeria as one example of how the process looks in practice.

FAQ

Is a hardware wallet 100% safe?
No. It protects against remote hacking very well, but it does nothing to protect against a lost or damaged device with no backup, and it doesn’t stop you from being tricked into signing a malicious transaction if you don’t check what you’re approving.

What happens if I lose my hardware wallet?
As long as you still have your recovery phrase, you can restore your funds to a new device. If you’ve lost both the device and the phrase, the funds are permanently inaccessible. There’s no support team that can reverse this.

Do I need a hardware wallet to use Novacrust?
No. Novacrust handles key security on its own infrastructure, so you can buy, sell, and hold USDT, USDC, and other supported crypto without managing a hardware device or a recovery phrase.

Is a custodial wallet less secure than a hardware wallet?
They protect against different things. A hardware wallet is stronger against remote hacking of an individual device. A well-run custodial platform removes the risk of losing your own keys, which is responsible for a large share of permanently lost crypto industry-wide.

What’s the biggest mistake people make with hardware wallets?
Storing the recovery phrase in only one place, often a photo on their phone, which defeats the purpose of taking keys offline in the first place. If you go the hardware route, the recovery phrase needs its own separate, offline backup.

Sign up to get started on Novacrust here.
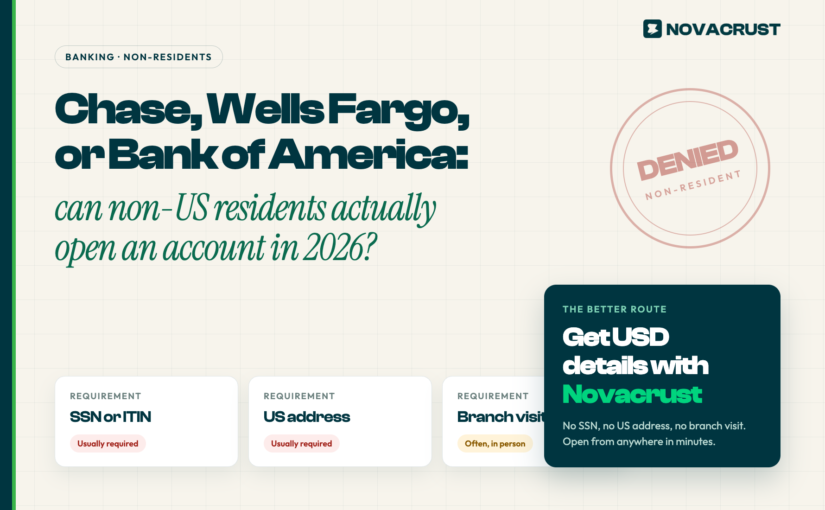
Chase, Wells Fargo, or Bank of America: Can Non-US Residents Actually Open an Account in 2026?

US federal law does not require a Social Security number to open a bank account. Under the Treasury Department’s Customer Identification Program rule, a foreign passport number and its country of issuance are legally enough to verify a non-US person. Walk into a Chase, Wells Fargo, or Bank of America branch with just a passport, though, and the experience usually tells a very different story.

That gap, between what the law technically allows and what each bank actually asks for, is where most non-resident account applications stall. Here is what each of the three biggest US banks really requires in 2026, and a faster route that skips the gap entirely.

What the law actually says

The Customer Identification Program rule, part of the Bank Secrecy Act, sets the federal floor for what a bank must collect before opening an account. For a non-US person, it accepts a taxpayer identification number, a passport number and country of issuance, an alien identification card number, or another government-issued document that shows nationality or residence and carries a photo. An SSN is one option on that list, not the only one.

In practice, individual banks are free to ask for more than the legal minimum, and Chase, Wells Fargo, and Bank of America all do.

Chase: an ITIN can stand in for an SSN, but you still need a US address

Chase accepts an Individual Taxpayer Identification Number as a substitute for an SSN on the application. Beyond that, it asks for official government-issued photo ID, which can be a passport, and proof of address such as a utility bill, a pay stub, or an employer letter dated within the last 60 days. Some Chase branches make exceptions for non-residents with extra documentation, but that varies by location and isn’t something you can count on walking in cold. Chase itself recommends confirming requirements with your specific branch before applying.

Bank of America: a scheduled conversation, not a self-serve form

Bank of America runs a dedicated path for international customers, split between international professionals and international students, but neither is a simple online signup. Both route you to book an appointment or a consultation with a specialist who confirms your eligibility and the documents you’ll need before you open anything. If you were hoping to finish this on your phone in ten minutes, that isn’t the process Bank of America has built for non-residents.

Wells Fargo: SSN or ITIN online, ID alone in a branch

Wells Fargo is the most specific of the three about what it will and won’t accept. To open an Everyday Checking account online, it asks for an SSN or ITIN, a US mailing address, and a mobile phone number. Without a US tax ID number, Wells Fargo’s own account-opening page states that non-US citizens can instead provide a government-issued ID that shows nationality or residence, but that path runs through a branch with two forms of identification, not the online application.

Read the fine print on all three banks and a pattern shows up fast: the identification rules have real flexibility, but the US address and the branch visit usually don’t.

The real wall isn’t the ID rule. It’s the address and the branch.

Every bank above technically allows a passport in place of an SSN somewhere in its process. None of them make that path a simple online form for someone who has never lived in the US. You need a US mailing address to receive statements and a debit card, and in most cases you need to show up in person, whether that’s a branch teller or a scheduled call with a specialist.

For freelancers, remote workers, and anyone getting paid in dollars from outside the US, that combination rules out the option entirely, not because the law says no, but because the paperwork does.

A USD Account that skips the address and the branch visit

A Novacrust USD Account gives you a real US account and routing number without a Social Security number, an ITIN, a US address, or a branch appointment. You open it from your phone, and it works the same way clients on Upwork, Fiverr, or a direct contract already expect: they send dollars to a US account number, and it lands in yours. For the fuller picture of how the traditional system treats non-residents and where Novacrust fits in, our guide to the US banking system for non-residents covers the rest of it.

If you’re a freelancer specifically weighing this against a traditional bank, a USD Account built for freelancers walks through how payouts from clients actually land, and opening one takes minutes, not a scheduled appointment.

FAQ

Do non-US residents legally need a Social Security number to open a US bank account?

No. Federal identification rules accept a foreign passport number and country of issuance as a valid alternative. Individual banks can still ask for more, and most do.

Can I open a Chase account without an SSN?

Chase accepts an ITIN as a substitute for an SSN on the application, but you’ll still need government photo ID and proof of a US address, and requirements can vary by branch.

Does Bank of America let non-residents open an account online?

Not as a simple self-serve form. Bank of America routes international professionals and international students through a scheduled appointment or consultation with a specialist first.

What does Wells Fargo accept if I don’t have an SSN or ITIN?

Wells Fargo’s online application requires an SSN or ITIN. Without one, its own guidance points non-US citizens to a branch visit with a government-issued ID showing nationality or residence, plus a second form of ID.

Is there a faster way to get a US account number without going through a traditional bank?

Yes. A Novacrust USD Account gives you a real US account and routing number from your phone, with no SSN, ITIN, US address, or branch visit required.

Sign up to get started on Novacrust here.
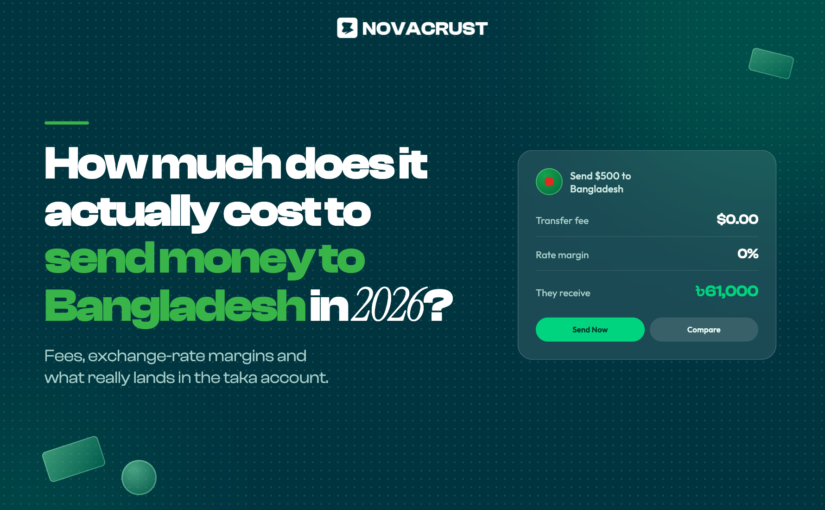
How Much Does It Actually Cost to Send Money to Bangladesh in 2026?

Bangladesh pulled in a record $35.56 billion in remittances in the fiscal year that just closed, up roughly 17.2 percent from $30.33 billion the year before, according to Bangladesh Bank data. The UAE, the US, the UK, and Saudi Arabia are the biggest sources, and most of that money is wired, walleted, or wired again before a single taka reaches a family’s hands. Every one of those steps has a price tag, and it is rarely the one advertised on the homepage.

The World Bank tracks exactly what senders pay on this corridor, and the numbers are not close. Here is what it actually costs to send $100, $500, and $1,000 to Bangladesh in 2026, where the fee hides, and the one government incentive that can put money back in your recipient’s pocket.

Where a transfer to Bangladesh quietly loses value

Three things chip away at the amount your family actually receives:

  • A marked-up exchange rate. This is where most providers make their real money. A transfer advertised as “no fee” can still cost more than one with a small, honest fee if the rate is padded underneath it.
  • A flat sending fee. Banks and card-funded transfers tend to charge the most here, sometimes stacked on top of the rate markup, not instead of it.
  • Cash pickup or agent markups. Picking up taka in cash instead of a direct bank or mobile wallet deposit usually costs more, since the provider is pricing in a physical agent network.

We walk through this same pattern across every corridor Novacrust supports in our guide to choosing the best way to send money internationally. The rule holds here too: judge a provider by what lands in Bangladesh, not by what it claims to charge.

What it actually costs to send money to Bangladesh

The World Bank’s Remittance Prices Worldwide database puts the average total cost of sending $200 from the United States to Bangladesh at 7.61 percent. The cheapest option it tracked, a bank-account-to-bank-account transfer, came in at 5.17 percent. The most expensive, a credit-card-funded transfer, ran 12.41 percent for the same amount and a slower delivery window.

Amount sentCheapest method tracked (5.17%)Corridor average (7.61%)Priciest method tracked (12.41%)
$100$5.17$7.61$12.41
$500$25.85$38.05$62.05
$1,000$51.70$76.10$124.10

Send $500 a month at the corridor average instead of the cheapest tracked method, and that gap alone runs over $145 a year. None of that ever reaches Bangladesh. It just funds whichever provider you picked.

The 2.5 percent incentive most senders miss

Bangladesh’s government pays a 2.5 percent cash incentive on remittances sent through formal, legally recognized banking and mobile financial service channels, and it confirmed the incentive continues in 2026. That money is credited on top of the exchange rate your recipient gets, but only when the transfer moves through a licensed provider, not an informal courier or an unregistered exchange. Sending $500 through a formal channel can mean an extra $12.50 landing in your recipient’s account for doing nothing differently except picking a legitimate provider.

It is the same principle we cover in our breakdown of what it costs to send money to Pakistan: the fastest way to lose value on a transfer is routing it through a channel that was never built to be transparent in the first place.

Bank account, bKash, or Nagad: what your recipient should use

Most Bangladeshi recipients now receive money one of two ways: straight into a bank account, or into a mobile financial service wallet like bKash or Nagad. Mobile wallets tend to win on speed and reach, since they do not require a recipient to visit a branch, but confirm your provider actually supports a direct wallet deposit before assuming it does. A transfer that has to route through an intermediary bank before reaching a wallet adds a step, and every extra step is another place a fee can hide.

The same tradeoff shows up whenever a large diaspora sends money home through a mix of banks and mobile wallets. Our guide to sending money to India covers a similar split between bank-linked transfers and app-based delivery, and the math for choosing between them is nearly identical.

A cheaper way to send to Bangladesh

A Novacrust account lets you hold US dollars and send to Bangladesh, or to 50+ other countries, without juggling a bank, a card, and a separate remittance app. You see the exchange rate before you confirm, and any fee is shown separately instead of buried in a padded rate. That matters most on a corridor like this one, where the gap between the cheapest and priciest method tracked by the World Bank is more than double.

FAQ

What’s the cheapest way to send money to Bangladesh?
A direct bank-account-to-bank-account transfer through a formal, licensed channel usually beats cash pickup and card-funded options, and it also qualifies for the government’s 2.5 percent incentive.

Can I send money directly to bKash or Nagad?
Many providers support direct deposits to mobile financial service wallets like bKash and Nagad. Confirm your provider offers a direct deposit rather than a routed transfer, since routed transfers usually take longer and cost more.

What is Bangladesh’s 2.5 percent remittance incentive?
It is a government cash incentive paid on top of the exchange rate for remittances sent through formal banking and mobile financial service channels. Bangladesh’s government confirmed it continues in 2026, and it does not apply to informal or unregistered transfer channels.

How long does a transfer to Bangladesh take?
Bank wires typically take one to three business days. Digital apps built for cross-border transfers, including Novacrust, usually settle in minutes once your funds are confirmed.

Final thoughts

With $35.56 billion already moving through official channels and growing every year, the provider you pick decides how much of that money actually does its job. Compare the real exchange rate before you send, confirm the channel qualifies for the 2.5 percent incentive, and treat a low advertised fee as the start of the question, not the answer.

Sign up to get started on Novacrust here.
Crypto Wallet Safety in Emerging Markets: The Questions People Actually Ask (2026)

One hack in 2023 emptied more than $100 million from Atomic Wallet users in a single incident, traced back to North Korea’s Lazarus Group. Meanwhile, hardware wallets from a single company, Ledger, now secure more than 20 percent of all the crypto value in the world. The gap between those two numbers is basically the whole case for choosing your wallet carefully, especially if you’re buying your first USDT from Lilongwe, Lusaka, or Port of Spain instead of San Francisco or London.

If you’re setting up a crypto wallet somewhere without a big local exchange scene, the basic questions rarely get answered simply. Here they are, straight, in the order people actually ask them.

Custodial or non-custodial: which one should you start with?

A custodial wallet, like the one built into Novacrust, holds your keys for you and lets you recover access if you lose your password. A non-custodial wallet puts you in full control, and full responsibility, since nobody can recover it for you if the recovery phrase is lost. Most people buying their first USDT or BTC are better off starting custodial, and moving funds to a non-custodial wallet later once they understand the tradeoffs. We cover this decision in more depth in our guide to custodial vs non-custodial wallets.

The questions people actually ask

Is it safe to buy USDT through P2P if there’s no official exchange in my country?
It can work, but P2P trading puts you at the mercy of a stranger’s word on both the rate and whether they’ll actually release the crypto after you pay. A platform that shows you the rate and network before you confirm removes most of that risk. Our guide to buying USDT safely in emerging markets walks through what to check before you trust a P2P seller.

Do I need a hardware wallet to get started, or is a custodial wallet fine?
A hardware wallet is worth it once you’re holding an amount you’d genuinely be upset to lose, generally more than you’d carry around in cash. Below that, a reputable custodial wallet with account recovery is a reasonable place to start, since the biggest real-world risk for beginners is losing access, not a wallet provider getting hacked.

What’s the single biggest risk when I’m setting up a wallet somewhere without a local exchange?
Fake apps and fake customer support. When there’s no local exchange to walk into, people search harder for help online, and that’s exactly where scammers set up fake wallet apps and fake “support agents” who ask for your recovery phrase. No legitimate wallet or exchange support agent will ever ask for it.

What should I never share, even with someone claiming to help me recover my wallet?
Your recovery phrase (also called a seed phrase) and your private keys. Anyone who has them has full, permanent access to your funds. A real support agent can help you troubleshoot an app; they can never ask for or need your recovery phrase to do it.

How do I know if a wallet app is legitimate before I download it?
Check that it’s listed on the official website of the coin or exchange you’re using, not just found through a search ad or a link someone sent you. Look at the download count and review history on the app store, and be suspicious of any wallet app released in the last few weeks with an unusually high number of five-star reviews.

What happens if I lose my recovery phrase?
On a non-custodial wallet, the funds are gone permanently. There’s no password reset and no customer support line that can restore it. That’s exactly why a custodial option, where a real support team can verify your identity and help you regain access, is worth considering while you’re still learning.

Which network should I use to send or receive USDT?
It depends on speed and fees, and the two most common networks work differently enough that sending to the wrong one can cost you the transfer entirely. Our breakdown of TRC20 vs ERC20 covers which one to pick and why.

Which apps do people in Africa actually use to buy and sell USDT and USDC?
Options include Yellow Card, Quidax, Busha, Binance P2P, and Novacrust, each with different strengths on rate, speed, and country coverage. Our comparison of the best apps to buy and sell USDT and USDC in Africa breaks down what to check before picking one.

Start with a wallet that shows you what’s happening

You shouldn’t need to guess which network you’re sending on, or trust a stranger’s word on the rate, just because there’s no local exchange nearby. Buy and hold USDT, USDC, BTC, ETH, SOL, and more on Novacrust, with the rate and network shown before you confirm anything.

Sign up to get started on Novacrust here.
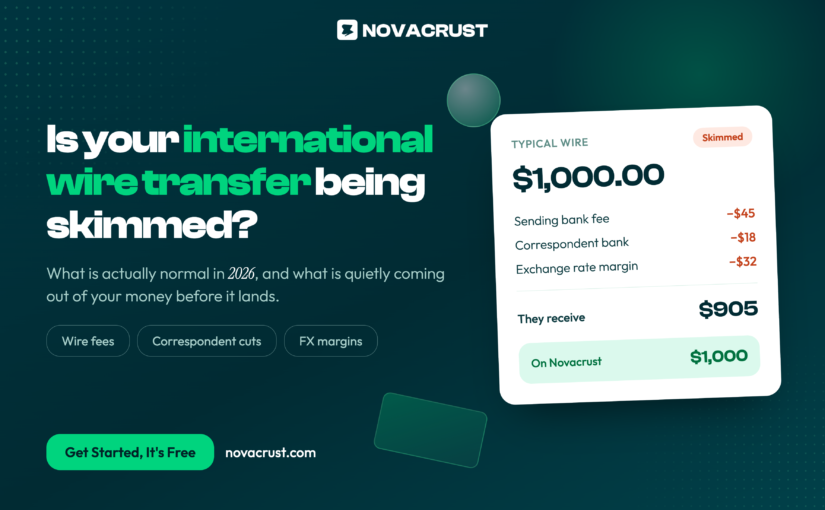
Is Your International Wire Transfer Being Skimmed? What’s Actually Normal in 2026

Send a $10,000 international wire and your recipient might see $9,930 land in their account. That missing $70 didn’t disappear by accident, and it usually isn’t fraud either. It went to banks neither of you chose, sitting quietly in the middle of the route your money took to get there.

If you’ve ever stared at a wire confirmation and wondered why the number doesn’t match what you sent, you’re not imagining things, and you’re not necessarily being scammed. Here’s what’s actually normal with international wires, what genuinely is a red flag, and how to stop losing money to banks you’ll never see on a statement.

Why wires shrink in transit

An international wire rarely travels directly from your bank to your recipient’s bank. It usually passes through one or more intermediary or correspondent banks along the way, banks that exist purely to move money between institutions that don’t have a direct relationship. Each one is entitled to take a “lifting fee,” typically $15 to $50 per bank, before passing the rest along.

Neither the sender nor the recipient picks which correspondent banks a wire routes through. That’s decided by the sending bank’s existing banking relationships, which is exactly why the same $10,000 transfer can lose $30 one month and $90 the next, with no explanation on either statement beyond a smaller final number.

Is this normal, or were you scammed?

A wire arriving a little short of what was sent is normal. It’s the standard cost of the SWIFT network, not a sign anyone did anything wrong. What isn’t normal, and is worth actually investigating, is different:

  • A wire that never arrives at all. A missing wire after several business days needs a trace request from your sending bank, not a shrug.
  • A deduction far larger than a few intermediary fees would explain. If tens of percent of the transfer vanished, that’s a rate or fee problem worth escalating, not routine lifting fees.
  • Being asked to pay a “release fee” directly to unblock funds. Legitimate correspondent bank deductions happen automatically before the money arrives. Nobody legitimate asks the recipient to wire money separately to release a stuck wire.

For the difference between the transfer rails themselves, our guide to ACH vs wire vs SWIFT breaks down which one your sender is actually using and why that decides both the speed and the fee.

How to avoid losing money to correspondent banks

The most reliable fix isn’t negotiating with your bank about fees you can’t see coming. It’s avoiding the international correspondent chain entirely when you can. A US-issued account and routing number lets a US-based client or employer pay you through the domestic ACH or wire network instead of an international SWIFT transfer, which means no correspondent banks sit in the middle taking their own cut.

That’s the gap a Novacrust USD Account closes. You get a real US account and routing number without needing an SSN or a US address, so anyone paying you from inside the US can send it as a domestic transfer instead of an international one. If you haven’t set one up yet, our guide to understanding the US banking system as a non-resident covers exactly what unlocks that access.

FAQ

Why did I receive less money than what was wired to me?
Correspondent banks in the middle of the transfer route each deduct a small “lifting fee,” usually $15 to $50 per bank, before the funds reach you. This is standard for international SWIFT wires and isn’t a sign of fraud on its own.

How many banks can a wire pass through?
It varies by route and depends on the sending bank’s existing relationships. Neither the sender nor the recipient chooses which correspondent banks are involved.

Can I avoid intermediary bank fees entirely?
Yes, by using a domestic transfer rail instead of an international one. A US account and routing number lets US-based senders pay you through ACH or a domestic wire, which doesn’t route through international correspondent banks.

Is it a scam if my wire arrives short?
Usually not, if the shortfall is a small amount consistent with one or two intermediary bank fees. It becomes a real concern if a large percentage is missing, the wire never arrives, or you’re asked to pay separately to “release” it.

What’s the difference between a USD Account and a regular bank account for receiving wires?
A USD Account issued through a platform like Novacrust still gives you a real US account and routing number, but without requiring US residency to open it, which is what lets you receive domestic-rail payments instead of only international ones.

The bottom line

A wire arriving a little short of what was sent is usually just the cost of the correspondent banking system doing its job. The real fix isn’t chasing down fees after the fact. It’s routing payments so those banks never get a chance to take a cut in the first place.

Sign up to get started on Novacrust here.
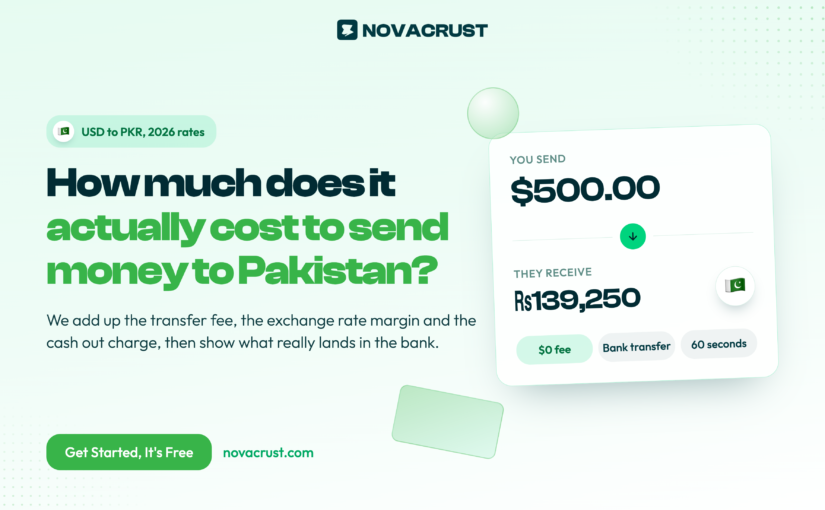
How Much Does It Actually Cost to Send Money to Pakistan in 2026?

Pakistan pulled in a record $41.6 billion in remittances in the fiscal year that just closed, up 8.6 percent from the year before, according to State Bank of Pakistan data. Saudi Arabia alone sent home $829.6 million in June, with the UAE, UK, and US close behind. That’s a lot of money moving through a system where the fee you’re quoted and the amount that actually lands are almost never the same number.

The United Nations set a global target of under 3 percent as the fair cost of sending remittances. The World Bank’s own tracking shows 28 countries still charge more than that on at least one major corridor. Here’s where a transfer to Pakistan actually loses money, and what it costs to send $100, $500, and $1,000 through the popular options.

Where a transfer to Pakistan quietly loses value

Three things eat into a transfer before your family or your recipient ever sees it:

  • A marked-up exchange rate. Most senders never compare the rate they’re offered to the actual market rate. The gap is often bigger than the flat fee on the receipt.
  • A flat sending fee on top of that rate. Banks and older wire services tend to charge the highest flat fees, sometimes $15 to $40 on a single transfer.
  • Cash pickup markups. Picking up rupees in cash instead of a direct bank or mobile wallet deposit usually costs more, since the provider is pricing in a physical agent network.

We break down the same pattern corridor by corridor in our guide to choosing the best way to send money internationally. The provider quoting the rate closest to the real market number, not the one with the flashiest app, is the one protecting your money.

What it actually costs to send money to Pakistan

Amount sentBank wire (typical)Cash pickup serviceDigital transfer app
$100$15 to $25 flat fee, plus rate markup$5 to $10 fee, weaker rate$1 to $3 fee, closer to market rate
$500$25 to $35, plus 3 to 5% rate margin$8 to $15, plus 4 to 6% rate marginLow flat fee, 1 to 2% rate margin
$1,000$30 to $45, plus rate margin$10 to $20, plus rate marginLow flat fee, competitive rate

The pattern holds across every corridor we’ve looked at: a bank wire’s flat fee looks manageable until you add the rate margin hiding behind it, and a small percentage on a large transfer adds up fast. On a $1,000 monthly transfer, a 4 percent all-in margin quietly removes $40 every single month, before any flat fee at all.

Where the money actually comes from

Gulf countries drive most of Pakistan’s remittance inflows. Saudi Arabia and the UAE together sent over $1.6 billion in June alone, with the UK and US making up most of the rest. If you’re sending from any of these corridors, the rate you’re offered should be checked against the market rate every time, not assumed to be fair because it’s from a recognized bank.

A cheaper way to send to Pakistan

A Novacrust account lets you hold US dollars and send to Pakistan, or to 50+ other countries, without stacking a bank, a card, and a separate remittance app on top of each other. You see the exchange rate before you confirm, and the fee is separate and visible, not folded into a padded rate. If you’re weighing wire transfer against a digital option for the first time, our comparison of ACH vs wire vs SWIFT covers how each one actually settles and what it costs.

FAQ

What’s the cheapest way to send money to Pakistan?
Whichever option quotes a rate closest to the real market rate and charges a small, transparent fee separately. Direct bank or mobile wallet deposit is almost always cheaper than cash pickup.

How much does it cost to send $500 to Pakistan?
Through a bank wire, expect $25 to $35 in flat fees plus a 3 to 5 percent rate margin. Through a digital transfer app with a transparent rate, the total cost is usually a fraction of that.

How long does a transfer to Pakistan take?
Bank wires typically take one to three business days. Digital apps built for cross-border transfers, including Novacrust, usually settle in minutes once your funds are confirmed.

Is a digital money transfer app safe for sending money to Pakistan?
A licensed, regulated transfer provider is not inherently less safe than a bank wire. Check that any provider you use is licensed to operate in the corridor you’re sending through before you commit to it.

Why did Pakistan’s remittances hit a record in 2026?
State Bank of Pakistan data points to stronger inflows from Gulf countries, tighter enforcement against informal transfer channels, and consolidation of exchange companies, all of which pushed more remittances through official, trackable routes.

Final thoughts

With $41.6 billion already flowing through official channels and the State Bank projecting even more next year, the fee structure you choose matters more than ever. Compare the real exchange rate before you send, every time, even if it only takes an extra minute.

Sign up to get started on Novacrust here.
Is Novacrust Legit? The Real Answer (2026 Guide)

Search “is Novacrust legit” and the first page doesn’t show you Novacrust. It shows you Scam Detector and ScamAdviser, two automated scoring sites that rate almost every fintech in the world the same way. That’s not because something is wrong. It’s because most companies never bother to answer the question directly. This one does.

The short answer

Yes. Novacrust is a real, operating platform used to buy, sell, and hold crypto (USDT, USDC, BTC, ETH, SOL, and more), send money to 50+ countries, open USD Accounts, trade gift cards, and use USD Virtual Cards. It holds a 3.8 out of 5 rating on Trustpilot from real, verified users, not a marketing number. Below is exactly what the third-party scam checkers say, what those scores actually measure, and how to verify all of it yourself in a few minutes.

Why scam checkers show up before Novacrust does

Sites like Scam Detector and ScamAdviser don’t investigate a company. They run an automated scan: domain age, SSL certificate, hosting provider, WHOIS privacy settings, and a handful of other technical signals, then output a number. No human reads your reviews or checks whether your support team answers tickets. Here’s what those scans currently say about Novacrust, in plain terms:

  • ScamAdviser concludes Novacrust is likely legitimate, citing domain age and a valid SSL certificate as positives. It flags that Novacrust’s domain registrar also hosts some low-trust-score sites, which pulls the number down even though it has nothing to do with Novacrust itself. This is a known limitation of registrar-based scoring, and ScamAdviser publishes a free process for any company to submit updated information for a rescan.
  • Scam Detector gives Novacrust a “medium/questionable” score of 51.6 out of 100. It doesn’t publish a public dispute process the way ScamAdviser does, so the more reliable fix is strengthening the underlying signals the algorithm reads (business registration visibility, social proof, and real user reviews) rather than appealing the number directly.

Neither of these is a substitute for checking the actual company. They’re a starting point, not a verdict.

How to verify any money app yourself, in 5 minutes

Whether you’re checking Novacrust or anyone else, here’s what actually tells you something:

  1. Real reviews, including the bad ones. A platform with only 5-star reviews is more suspicious than one with a mixed rating and visible responses. Novacrust’s Trustpilot page shows both, at a 3.8 average.
  2. How complaints get handled. Look for whether the company responds to negative reviews at all, and how fast. Slow responses are a real fix a company can make; a total absence of responses is a bigger flag.
  3. Security features you can see for yourself. Two-factor authentication, KYC verification before payouts, and the ability to freeze or delete cards on demand are all things you can test in an account before you ever fund it. Novacrust’s own security setup is covered in detail in our guide to security features in virtual USD cards.
  4. Whether it asks you to pay before it delivers, or after. Legitimate platforms verify a transaction first and pay out after, not before. If a platform asks you to send money and “trust us” for what comes back, that’s the actual red flag, regardless of what a scam-checker score says.
  5. Whether the same checks apply to licensed providers, not just crypto apps. The same due-diligence steps apply to any provider moving your money, including mobile money and bank-transfer apps. We cover the full version of this checklist in how to check if a money transfer or mobile money app is actually licensed.

What an actual scam looks like, versus a legitimate platform with rough edges

It helps to separate the two, because they get lumped together constantly. A scam asks you to send money first and disappears after. It has no verifiable reviews at all, positive or negative, because it doesn’t stay online long enough to collect them. It has no real support channel, just a form that goes nowhere. And it can’t be found on Trustpilot, ScamAdviser, or anywhere else, because it was never built to last.

A legitimate platform with rough edges looks different. It has a review history you can read, including complaints, because it’s been operating long enough to accumulate both praise and criticism. It responds to support tickets, even slowly. It shows you the rate before you confirm, and it verifies your identity before it pays out, not the other way around. Slow support and a mixed rating are real problems worth fixing. They’re not the same thing as a scam, and treating them as identical makes it harder to spot the platforms that actually deserve the label.

Community presence is another useful signal. Check whether a platform has active, ongoing channels (X, Telegram, a real support inbox) where people are actually asking questions and getting answers, rather than a single announcement post from years ago. An active, current presence is a much stronger signal than a scam-checker score on its own.

What actually makes Novacrust safe to use

Beyond the third-party scores, here’s what you can check directly in the product:

  • KYC before payout. Verification is required before funds move out, which is standard practice for a compliant fintech and directly limits fraud on both sides of a transaction.
  • Transparent rates. Rates and fees are shown before you confirm a transaction, not buried until the last screen.
  • A support team that responds. If you run into an issue, escalate it and give Novacrust the chance to fix it. Most legitimate complaints get resolved faster through direct support than through a public review, and every resolved issue improves the real trust signals that scam-checker sites eventually pick up on too.

If you’re deciding between buying and selling crypto safely on any platform, not just Novacrust, our guide to buying USDT safely in 2026 covers the same verification habits in more detail.

Frequently asked questions

Is Novacrust legit?
Yes. Novacrust is an operating platform with a 3.8 Trustpilot rating from real users, visible security features, and a KYC process required before payouts.

Is Novacrust safe for sending money and crypto?
Novacrust requires identity verification before funds move out and shows rates and fees upfront. Combine that with the verification checklist above before funding any account, including this one.

Why does Novacrust show a low score on Scam Detector or ScamAdviser?
Those scores are automated and based on technical signals like domain age and hosting, not a human review of the company. ScamAdviser itself lists Novacrust’s domain age and SSL certificate as positives while flagging an unrelated registrar issue that lowers the number.

Why does Trustpilot list Novacrust under a “high-risk investment” category?
Trustpilot’s business categories are broad and self-selected from a fixed list. “High-risk investment” reflects the general category crypto platforms are grouped under, not a specific finding about Novacrust.

What’s the fastest way to confirm any platform is legitimate before I fund it?
Check the reviews (including the negative ones), test the security features with a small amount first, and confirm the platform verifies before it pays out rather than the other way around.

Does a mixed Trustpilot rating mean I shouldn’t use a platform?
No. A mixed rating with visible, specific complaints is usually a sign the reviews are real. Be more cautious of a rating that’s either suspiciously perfect or has no reviews at all.

See it for yourself

The fastest way to know if Novacrust is legit is to open an account and check the security features, rates, and verification steps yourself. Get Started. It’s Free.

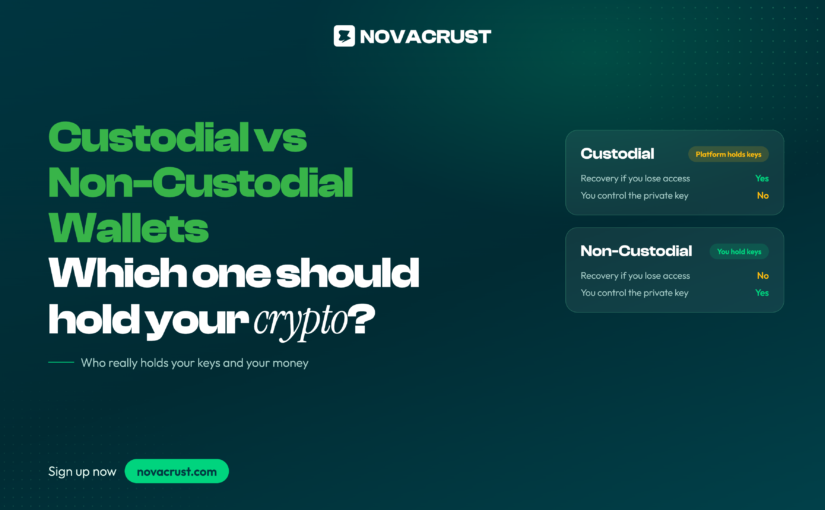
Custodial vs Non-Custodial Wallets: Which One Should Hold Your Crypto?

Crypto theft hit $3.4 billion in 2025, and the FBI puts crypto related fraud losses at a record $11.4 billion for the same year. Most of that money didn’t disappear because blockchains got hacked. It disappeared because someone lost control of a private key, trusted the wrong app, or sent funds to a wallet with no recovery option. The question of who actually holds your keys, you or a platform, is the single biggest safety decision you make when you buy or sell crypto.

That question has a name: custodial versus non-custodial. Here’s what each one actually means, and how to decide which one fits how you use crypto.

What “custodial” and “non-custodial” actually mean

A custodial wallet is one where a platform holds your private keys on your behalf, the same way a bank holds your cash. You log in with a password, and the platform moves funds for you. A non-custodial wallet is one where you hold your own private keys, usually as a 12 or 24 word recovery phrase, and no company can freeze, recover, or move your funds without you.

The crypto community sums up the tradeoff in one phrase: not your keys, not your coins. It’s a fair warning, but it’s not the whole story. Self custody removes a third party from the equation. It also removes the safety net that third party provides. Ledger’s academy breaks down the mechanics in more depth if you want the full technical picture.

Six rules for picking the right type of wallet

  1. Match the wallet to how often you trade. If you’re buying and selling regularly, a custodial platform with fast, in-app execution beats moving funds to a separate wallet every time.
  2. Match it to how much you’re holding. Small, active balances are fine in a custodial account. Large amounts you don’t plan to touch for months are usually safer under your own keys, split across secure backups.
  3. Know what happens if you forget your password or phrase. A custodial platform can usually help you recover account access. A lost recovery phrase on a non-custodial wallet is gone for good. There’s no support line that gets it back.
  4. Check who’s actually licensed. A custodial platform with clear regulatory standing gives you recourse if something goes wrong. An anonymous wallet provider or unregulated exchange gives you none.
  5. Never store your recovery phrase digitally. Not in a notes app, not in a photo, not in an email draft. Screenshots and cloud backups are exactly what attackers search for.
  6. Test with a small amount first. Whether you’re trying a new custodial platform or setting up your first non-custodial wallet, send a small amount through before you commit your full balance.

Custodial vs non-custodial, side by side

Factor Custodial Non-custodial
Who holds the keys The platform You
Account recovery Usually possible Not possible without your phrase
Speed for buying/selling Fast, in-app Slower, needs a transfer step
Best for Active trading, everyday use Long-term storage, large balances
Biggest risk Platform gets hacked or mismanaged You lose your phrase or get phished

Where Novacrust fits

Novacrust runs as a custodial platform. When you buy or sell USDT, USDC, BTC, ETH, SOL, and more, your funds sit in your Novacrust wallet, and the platform handles the key management and network security behind the scenes. That’s the same tradeoff every custodial exchange makes: convenience and recovery options, in exchange for trusting the platform’s security.

If you’re actively trading, converting to local currency, or moving funds between crypto and a USD Account, a custodial setup like Novacrust removes the extra step of managing your own keys for every transaction. We’ve covered how to avoid the P2P scams that catch people buying USDT the hard way, and how the major buy/sell apps compare if you’re still choosing a platform.

When a non-custodial wallet still makes sense

If you’re holding a large balance for months or years, want direct interaction with decentralized apps, or simply don’t want any third party able to freeze your funds, a non-custodial wallet is the right tool. Many people run both: a custodial platform for active buying, selling, and spending, and a non-custodial wallet for savings they don’t touch often. If you move funds between the two, always double check the network before you send. Sending USDT on the wrong network is one of the most common ways people lose funds that has nothing to do with hacking at all, which is why picking the right network matters as much as picking the right wallet.

FAQ

Is Coinbase a custodial or non-custodial wallet?

The main Coinbase exchange account is custodial. Coinbase Wallet, a separate app, is non-custodial and gives you your own keys.

Is Trust Wallet custodial or non-custodial?

Trust Wallet is non-custodial. You control the recovery phrase, and no company can restore access if you lose it.

Are non-custodial wallets safer than custodial ones?

Neither is universally safer. Non-custodial wallets remove platform risk but add personal responsibility for keeping your keys secure. Custodial platforms remove that responsibility but concentrate risk on the platform’s own security.

What happens if I lose my non-custodial wallet’s recovery phrase?

Your funds become permanently inaccessible. There’s no password reset and no support team that can recover it, which is why backing up your phrase correctly matters more than almost anything else in crypto.

Can I move funds between a custodial platform and a non-custodial wallet?

Yes. Most people do exactly this: buy or sell on a custodial platform like Novacrust, then withdraw to a non-custodial wallet for longer-term storage. Just confirm the network matches on both ends before you send.

Buy and sell crypto without managing your own keys

Novacrust handles the custody, security, and network checks so you can buy, sell, and hold USDT, USDC, BTC, ETH, SOL, and more without setting up a separate wallet first. Sign up to get started on Novacrust here.
He Started With a $10 Gig. Here’s How Tiamiyu Mustapha Built a Global Freelance Career.

Mustafa’s story is one many young African freelancers will recognize, no clear roadmap, few resources, and a lot of trial and error before things started to click. In this interview, he shares how he moved from watching free tutorials online to working with international clients as a marketer and digital creator, the payment struggles that nearly held him back, and the lessons he’s picked up along the way.

Let’s dive in.

Can you briefly introduce yourself and tell us what you do?

My name is Tiamiyu Mustapha. I’m a freelancer, Network marketer, and creator.

How did your journey into the digital or creative space begin?

Honestly, it wasn’t something I planned from the start. I didn’t go in with a fixed idea of exactly where it would lead, I was just drawn to tech and digital skills, and I started learning out of ambition more than a clear plan. I didn’t have anyone holding my hand through it. I had to figure things out mostly on my own, learning as I went and leaning on my own experience to move forward. Thanks to the community I found myself. 

What first inspired you to start building your career online?

I started learning digital skills seriously through free resources,  watching videos and using online platforms to teach myself, since I didn’t have money for paid courses. A lot of people in my community didn’t know much about Ai Skills at the time, so there wasn’t a lot of guidance available locally. I leaned on my community and the resources I could find, and just kept learning consistently until I felt ready to start taking on real work.

What were some of the biggest challenges you faced when starting out, especially working internationally?

The biggest challenge was not having enough resources to work properly with international clients, the tools, the platforms, even reliable access to some of the services other freelancers around the world could use easily. I had to make do with limited resources and figure out workarounds, watching tutorials and reading up online just to close the gap.

Did you ever face issues receiving payments from international clients? How did that impact your growth?

Yes, definitely. Payment issues are something almost every freelancer I know has dealt with at some point. I had accounts get suspended, and I had to find alternative platforms just to keep receiving money safely. It’s a real challenge, a lot of freelancers, especially Nigerians, don’t have access to certain international payment platforms, so you’re constantly looking for workarounds just to get paid for work you’ve already done.

What was your very first international payment experience like?

My very first paid gig was worth $10. I was doing marketing work on a freelance platform at the time. It doesn’t sound like much now, but I remember exactly how it felt,  that first payment proved to me that this could actually work, and I knew I had to keep going from there.

How did you handle the payment challenges at the time?

Mostly through hard work and building trust with clients over time. I focused on establishing myself with reliable platforms and being consistent, so clients could trust that I’d deliver, and in turn, I could trust that I’d get paid. It wasn’t perfect, but staying consistent helped me manage the uncertainty.

In your opinion, how important is having a reliable dollar payment account for freelancers and digital creators?

It’s extremely important. A lot of the setbacks I faced early on came down to not having stable, reliable ways to receive money from clients abroad. When you don’t have that, you lose time, you lose trust with clients, and sometimes you lose money outright. Having a dependable payment system isn’t a luxury for freelancers working internationally,  it’s foundational.

Was there a particular breakthrough moment that changed your trajectory?

Yes. Things started to shift when I leaned into AI-related work. I noticed the opportunities opening up in that space and decided to position myself early. One client reached out wanting help creating an AI-focused course, outlining the content and putting the material together. It was new territory for me, but I took it on, and it ended up being a turning point that opened doors to more serious, better-paying projects.

What skills or mindset helped you grow the most in your career?

I would say adaptability and consistency. Working in AI and freelancing means things change very fast, so I’ve had to keep learning new tools and improving my skills. I also learned not to give up easily, especially when things were slow or difficult.

What lessons would you share with African freelancers looking to work with global clients today?

My biggest advice is to focus on your skills and the value you can provide, not your location. Global clients care about results, communication, professionalism, and reliability. Also, build a strong portfolio because sometimes your work can speak louder than your qualifications.

How do you stay consistent and motivated even during slow or challenging periods?

I remind myself there’s no going back. There will be slow periods and downtimes, that’s normal. But I’ve learned to keep showing up regardless of the situation, because consistency is what eventually pays off, even when it doesn’t feel like it at the moment.

What is one honest truth about building a global career that nobody tells young African creators and freelancers?

It takes longer and requires more patience than most people expect. You will face rejection, difficult clients, payment challenges, and periods where things are slow. But if you keep improving and stay consistent, opportunities can come from places you never expected.

Novacrust is a platform that makes receiving international payments fast, simple, and secure. How do you think having access to a solution like this could help freelancers like you?

It would make a big difference because receiving international payments can sometimes be stressful for African freelancers. A simple and secure platform would help us get paid faster and focus more on delivering great work instead of worrying about payment methods.

Would you consider signing up for a platform like Novacrust to make getting paid from international clients easier? Why or why not?

Yes, definitely especially if it is reliable, secure, and makes it easy for international clients to pay me. As someone who works with clients from different countries, having a smooth payment process is very important.

Can you please tell us the maximum range of your salary in a month?

As a freelancer, my income is not fixed and can vary depending on the projects I’m working on. In a good month, I can make anywhere from $1,500 to $3,000 or more, depending on the size and number of projects.

Mustafa’s story shows that you don’t need a perfect plan to start. You just need to keep learning, keep showing up, and keep improving. From a $10 gig to earning thousands of dollars a month, his journey proves that consistency pays off, even when growth feels slow. For young African freelancers and creators, his message is simple: your skills can take you anywhere, and the right tools, like reliable payment platforms, can make the journey a lot easier.